Corporate Life Insurance Planning

Corporate Life Insurance Planning: Protect, Reward, and Plan for the Future

Running a business in often means wearing multiple hats—owner, leader, and long-term planner. But have you ever thought about what happens if you or a key person in your company passes away unexpectedly? Or how you might use your corporation to support retirement, reward top talent, or prepare for taxes when transitioning ownership?

Corporate life insurance is one of the most flexible and underused tools available to business owners. It helps protect your company, reduce taxes, and build lasting value—both during your working years and when it’s time to pass the business on.

Let’s look at how business owners are using corporate-owned life insurance to protect their companies and their families while preparing for the future.
brandableContent

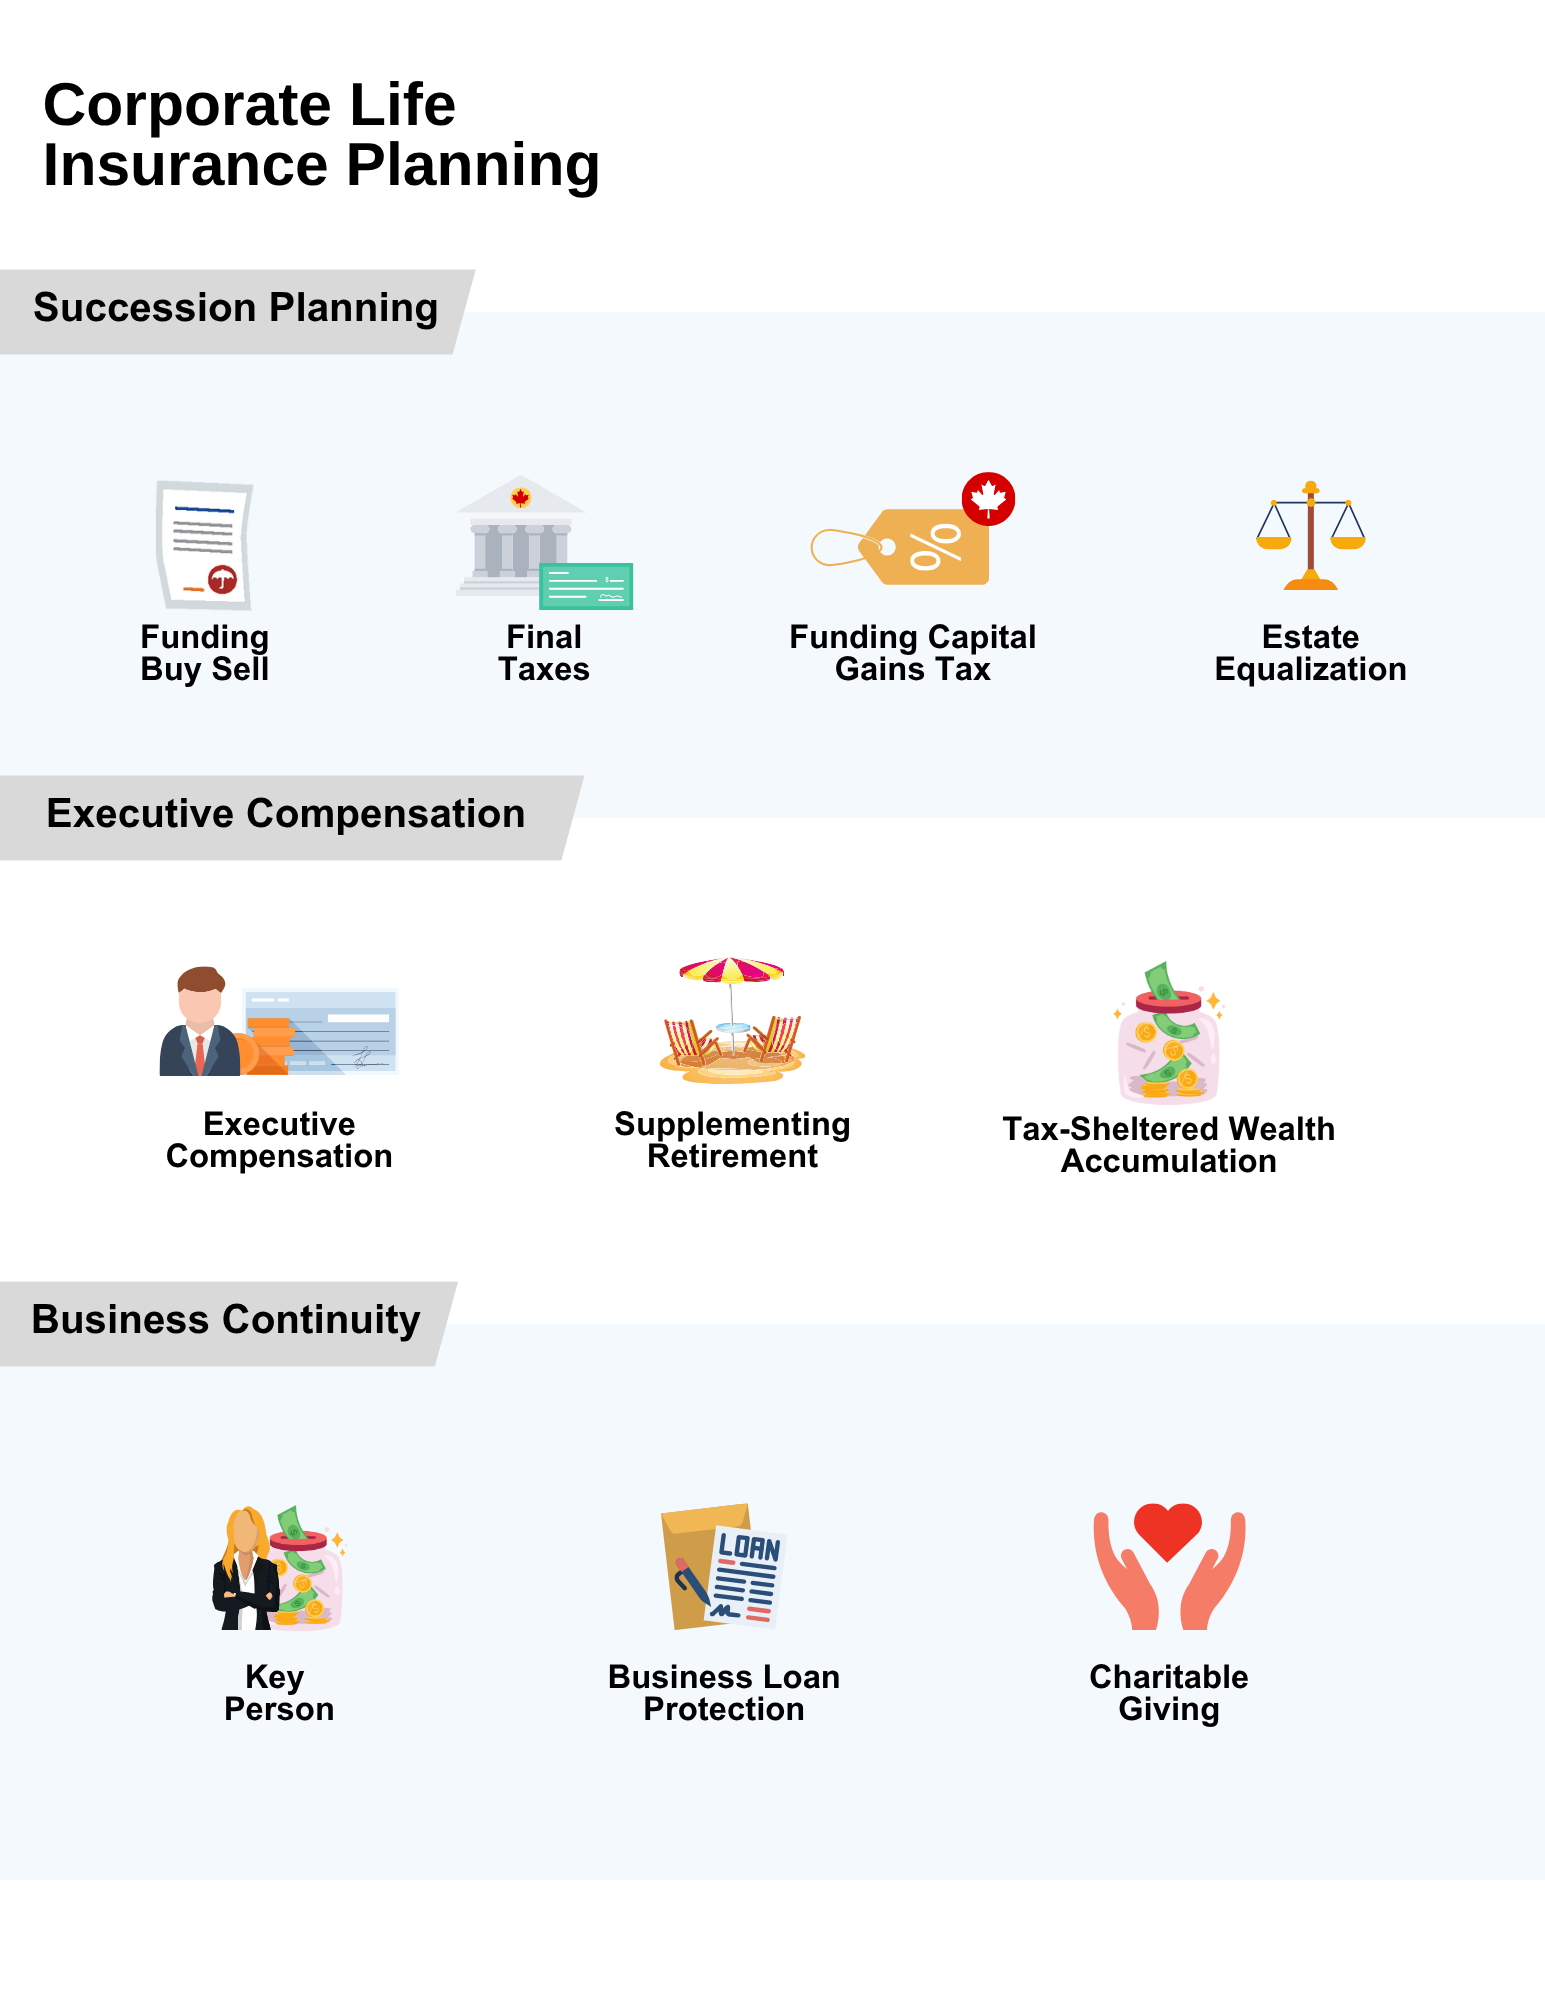
Succession Planning: Make Transitions Smooth and Tax-Smart

For many business owners, their company is one of their largest assets. But passing it on—whether to family or a partner—comes with major financial challenges. Life insurance can help.

Funding a Buy-Sell Agreement

If you have a business partner, a buy-sell agreement ensures that if one of you passes away, the other can buy the shares from the deceased’s estate. The problem? That buyout requires cash—often hundreds of thousands, if not millions. Life insurance is a cost-effective way to fund that agreement, so ownership stays in the right hands without putting a strain on the business or the family.

Covering Final Taxes and Capital Gains

When a business owner dies, the Canada Revenue Agency treats it as if they sold their shares—even if they didn’t. This “deemed disposition” creates a tax bill that can surprise even the most prepared families. Life insurance provides a tax-free lump sum that the corporation can use to cover this cost, helping preserve the value of the business and avoid selling off assets under pressure.

Estate Equalization

If you plan to leave the business to one child but want to treat your other children fairly, life insurance can help. The business goes to the child who’s involved, while other beneficiaries receive the life insurance proceeds. It’s a clean, tax-efficient way to avoid family conflict and keep the business whole.

Executive Compensation: Attract and Retain Top Talent

In a competitive hiring environment, offering the right benefits can make all the difference. Life insurance isn’t just about protection—it can be a powerful way to reward and retain your most valuable people.

Executive Compensation Strategies

Life insurance can be part of a compensation package that rewards top performers, especially those who are key to the company’s success. Whether structured as a bonus plan or part of a long-term incentive, this can be a powerful way to align goals and build loyalty.

Supplementing Retirement

Permanent life insurance policies—such as whole life or universal life—can accumulate cash value over time. This cash value grows tax-deferred and can later be accessed through policy loans or collateralized lending. For business owners and executives, this provides an additional, flexible income source in retirement, especially when RRSP and TFSA contribution limits have already been reached. It allows the corporation to efficiently use surplus cash while providing long-term financial flexibility and security.

Tax-Sheltered Wealth Accumulation

The cash value inside a permanent life insurance policy grows on a tax-deferred basis. When a corporation owns the policy, this growth can be especially strategic. It allows the business to use surplus cash to build value in a tax-efficient way, diversify beyond traditional investments, and potentially access funds later with fewer tax consequences. This approach is particularly useful for businesses with retained earnings that would otherwise be subject to higher corporate tax rates.

Business Continuity: Protect What You’ve Built

An unexpected death can do more than cause emotional pain—it can disrupt operations, shake client confidence, and even put the business at risk. Insurance helps ensure your company can keep going.

Key Person Protection

If you or someone else is essential to the day-to-day success of your business, losing that person could be a major financial blow. A life insurance policy on that individual can help the business recover, cover short-term losses, and fund the search for a replacement.

Business Loan Protection

Many lenders require insurance on owners or key executives as a condition of financing. If that person passes away, life insurance ensures the loan is paid off, protecting both the lender and the company’s assets. It can also unlock better lending terms and help avoid personal guarantees.

Charitable Giving Through the Corporation

For business owners looking to give back, corporate life insurance can also be used to support charitable causes. The business can own a policy and name a charity as the beneficiary—creating a lasting impact while offering potential tax benefits.

Bringing It All Together

Corporate life insurance isn’t just about “what if”—it’s about building a stronger, more resilient business and unlocking smart ways to manage wealth inside your company. Whether you’re focused on succession, rewarding your team, or protecting operations, insurance can help you take action today that pays off for years to come.

If you haven’t reviewed your corporate insurance strategy recently, now’s a great time to take a fresh look.

Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.

Financial Checklist for New Parents in Canada

What to Do Financially When You Have a Baby

A new baby brings a lot of joy, and a lot of new to-do lists. Most of them are about feeding schedules and car seats. But a few items on the list are about money, and they matter more than you might think.

You do not need to do everything at once. A newborn keeps you busy enough. The steps below can be spread out over the first few months. Think of this as a simple checklist you can come back to as you find the time and energy.

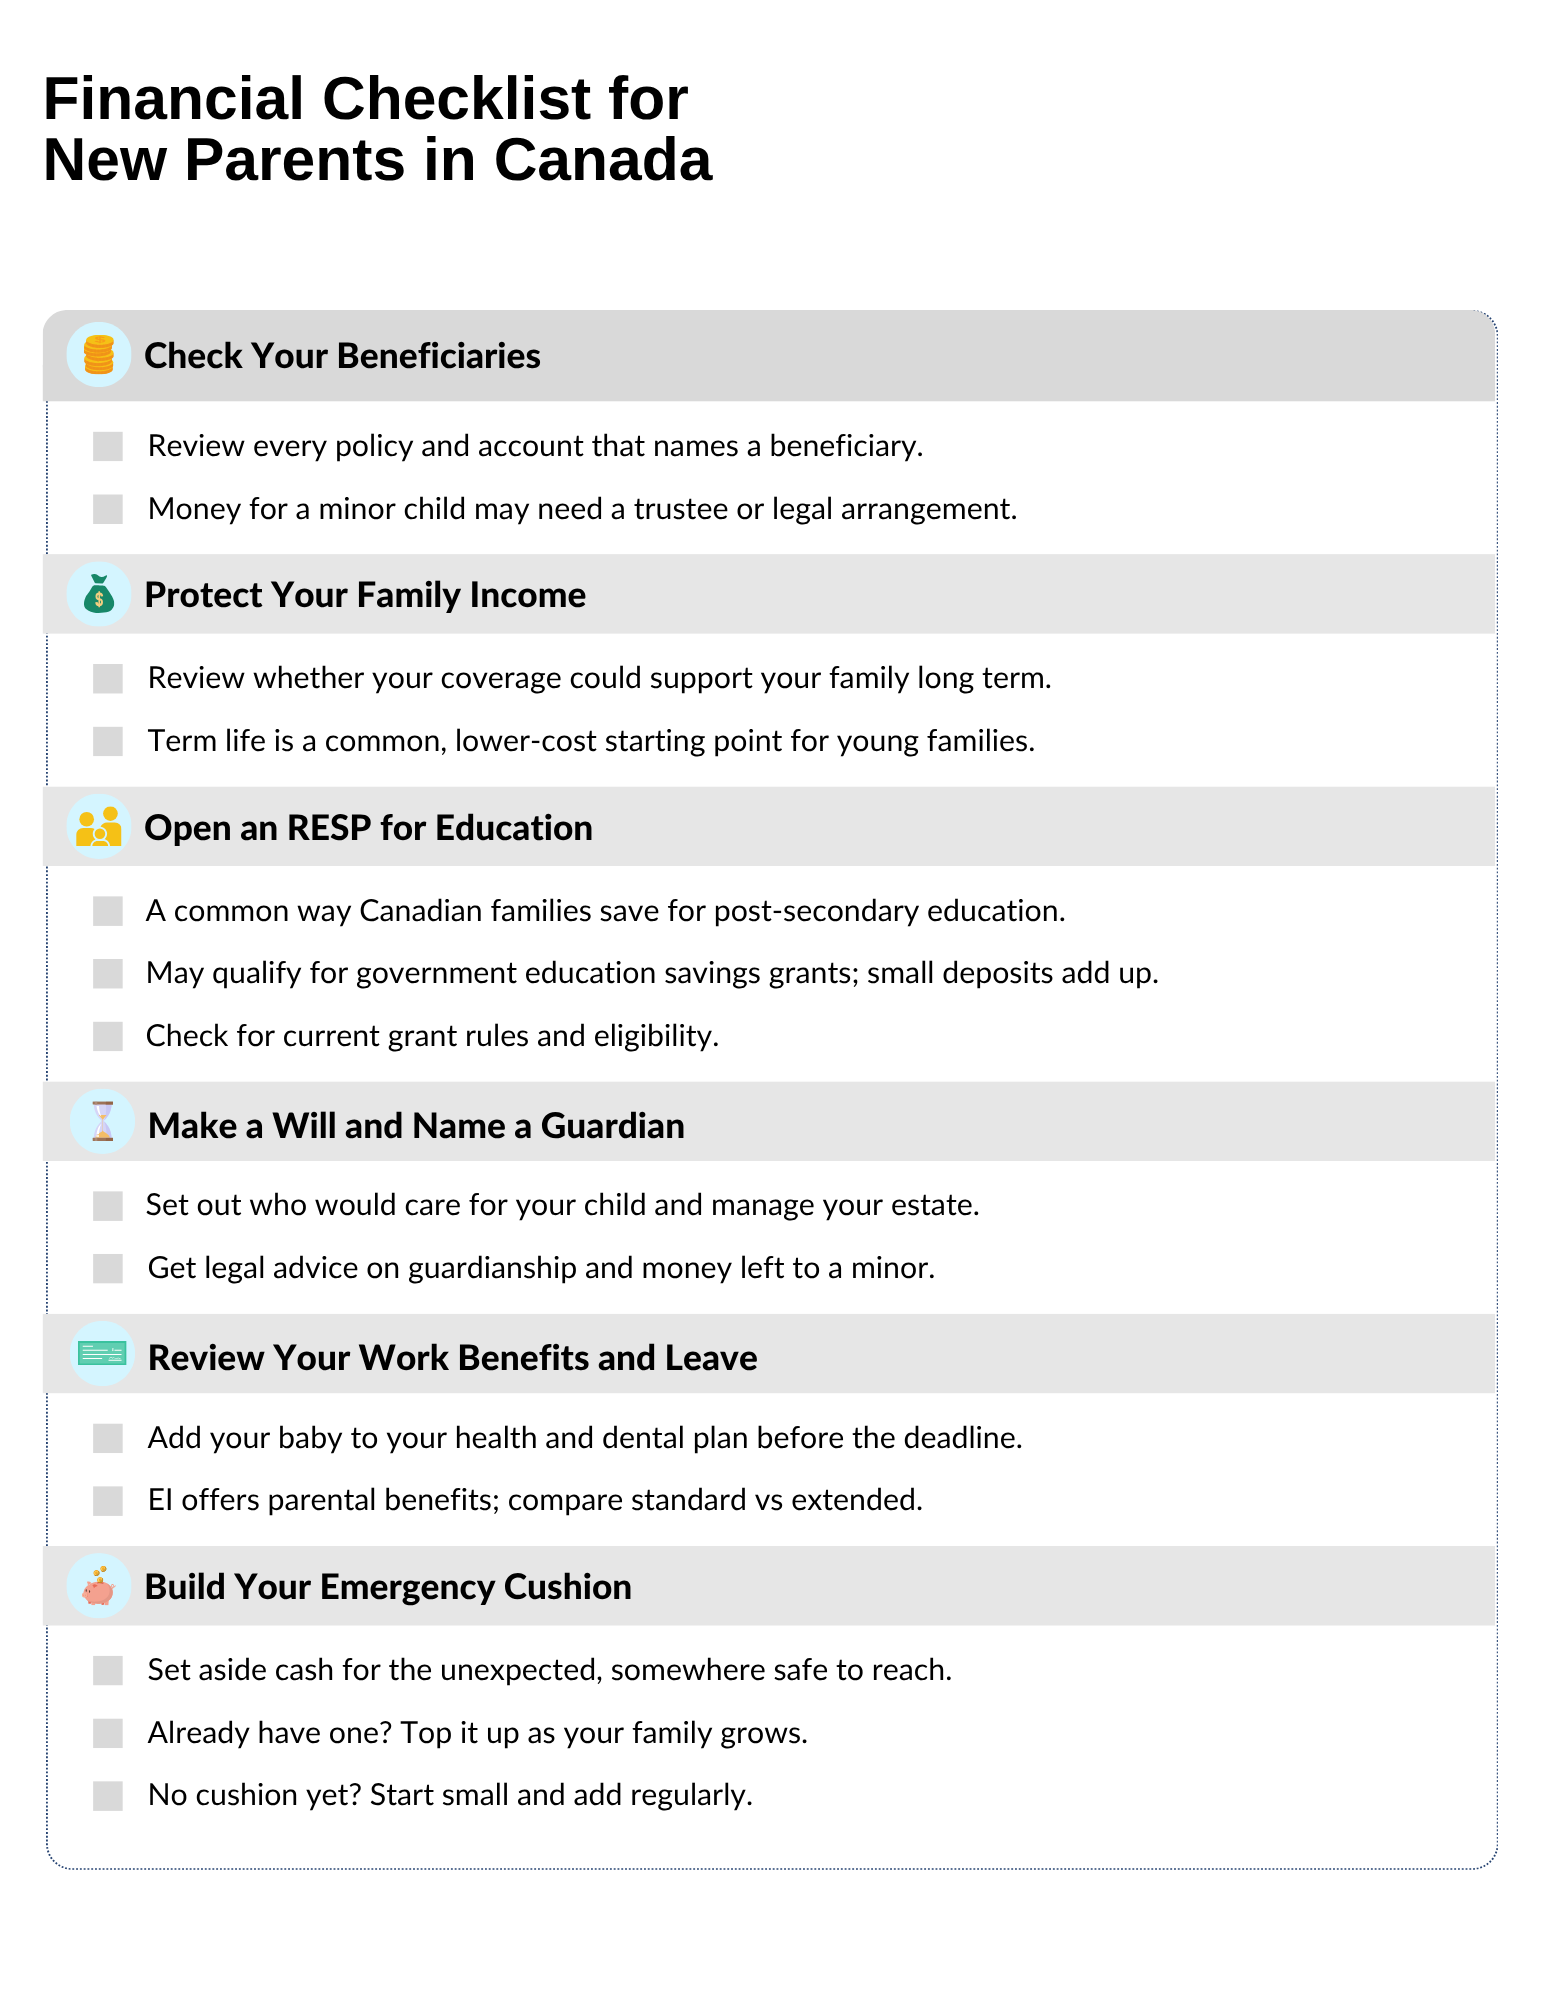
Check Your Beneficiaries

A beneficiary is the person who receives the money from your life insurance or certain registered accounts after you pass away. Many people set these up years ago and never look at them again.

Now is a good time to check. You may want to add your partner, update an older choice, or think through how money should be handled for your child. If you want money to go to a minor child, it may need to be managed through a trustee or other legal arrangement until the child is of age, depending on the asset and the province.

The key point is simple. Look at every policy and account that names a beneficiary, and make sure the names and instructions still match the life you have today.

Protect Your Family Income With Life Insurance

When it was just you, or just you and your partner, a gap in income may have been easier to manage. With a baby who depends on you, the stakes are higher. Life insurance can help protect your family financially if something happens to you, so they can keep up with housing costs, bills, and daily expenses.

For many young families, term life insurance is a common starting point. It covers you for a set number of years, often when your children are young and your financial obligations are highest. The premiums are usually lower than permanent coverage, which can make it easier to fit into a new-parent budget.

Your need for coverage often increases when you have a child. It is worth checking whether your current coverage, including any through work, would be enough to support your family for more than just the short term.

brandableContent

Open an RESP for Education

A Registered Education Savings Plan, or RESP, is a common way Canadian families save for a child’s post-secondary education. One reason many parents use it is the government support that can come with it through education savings grants.

You do not need a large amount to begin. Even small, regular deposits can add up over time. Check canada.ca for the current grant rules, contribution details, and eligibility requirements.

Make a Will and Name a Guardian

This is the step many new parents put off, and it is one of the most important. A will helps set out who would care for your child and how your estate should be handled if you and your partner die.

For parents, the most important part is often naming the person you want to care for your child. In BC, a will can express your wishes about guardianship, but it is also important to work with proper legal advice so your will deals clearly with both the care of your child and the management of any money left to a minor.

If you already have a will, a new baby is a good reason to review it. Add your child, confirm your choices, and make sure your estate plan still reflects your wishes.

Review Your Work Benefits and Leave

Your job may offer more help than you realize. Many group benefit plans allow you to add a new dependent, but the deadline depends on the plan. Check with your human resources team or plan administrator as soon as possible after the birth so you do not miss the deadline for health and dental coverage.

Employment Insurance, or EI, also offers maternity and parental benefits for eligible parents. Parents can choose standard or extended parental benefits, and the timing and number of weeks differ between the two options, so it is important to review the current rules before applying.

Build Your Emergency Cushion

A baby comes with surprises, and some of them cost money. An emergency cushion is simply cash set aside for the unexpected, kept somewhere safe and easy to reach.

If you already have one, this is a good time to top it up. A larger family often means larger surprise costs. If you do not have one yet, start small. Even a modest amount set aside regularly can help keep a rough week from becoming a money crisis.

A Calm Way to Start

That is a full list, and you do not have to tackle it all at once. Pick one item this week. Maybe it is checking a beneficiary, or asking work about adding your baby to your benefits. Small steps, taken one at a time, can help build a stronger financial foundation for your growing family.

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

Sources:

What Is Participating Whole Life Insurance?

What Is Participating Whole Life Insurance?

Most people buy life insurance for one reason: to make sure their family is protected if something happens to them. But there is a type of life insurance that does something more – it builds value over time while you are still alive. That type is called participating whole life insurance, and it works very differently from the term policies most Canadians are familiar with.

Here is what it means, how it works, and whether it might be a fit for you.

Permanent Coverage That Does Not Expire

Term life insurance covers you for a set period – 10, 20, or 30 years. Participating whole life insurance is permanent. It covers you for your entire life, as long as premiums are paid, and the death benefit is guaranteed.

That permanence is the first major difference. But the bigger difference is what happens to your premiums while you are alive.

With a term policy, your premiums go entirely toward the cost of insurance. With participating whole life, the insurer pools premiums into a participating account that is professionally managed. Dividends may be paid when the account’s experience is favourable, based on factors such as investment returns, expenses, and mortality experience.

How Dividends Work

The word “dividend” here is different from stock dividends. In the context of a participating whole life policy, a dividend is a share of the insurance company’s surplus – essentially, the company returning a portion of the money when investment performance, claims experience, and expenses go better than expected.

These dividends are not guaranteed. They are declared each year by the insurance company based on how the participating account performed. That said, many Canadian participating insurers have long histories of paying dividends, though past performance does not guarantee future results.

When you receive a dividend, you have a few options for how to use it:

  • Take it as cash. The dividend is paid to you directly.

  • Apply it to your premium. It reduces how much you pay out of pocket.

  • Buy additional paid-up insurance. This is the most common choice. The dividend purchases more coverage, which in turn earns its own dividends. Over time, this compounds.

  • Leave it on deposit. The dividend sits with the insurer and earns interest.

Most policyholders who hold participating whole life for the long term choose to purchase additional paid-up insurance, because it accelerates both the death benefit and the cash value of the policy.

The Cash Value

One of the most distinctive features of a participating whole life policy is that it builds cash value. The policy builds guaranteed cash value as part of its structure, and dividends can add a non-guaranteed layer of growth if they are used to buy paid-up additions.

The policy accumulates cash value that you may be able to access, subject to policy terms, in a few ways:

  • Policy loans. You can borrow against the cash value without going through a lender or credit check. Policy loans do not have fixed repayment schedules, but any unpaid balance can reduce the death benefit.

  • Surrendering the policy. If you decide you no longer need the coverage, you can cancel the policy and receive the accumulated surrender value. The tax treatment on surrender can be technical and depends on the policy’s adjusted cost basis — the disclaimer at the end of this article applies here.

The cash value grows on a guaranteed basis, separate from the dividends. The dividends, if used to purchase paid-up additions, add a non-guaranteed layer of growth on top.

Who Is This Type of Policy For?

Participating whole life is not the right fit for every situation. Because premiums are higher than term insurance, it is most commonly used by people who have a long-term need for life insurance and who can sustain the premium over time.

Some of the most common situations where it makes sense:

Families building long-term wealth. For parents who want to ensure a guaranteed death benefit no matter when they pass, plus build a tax-advantaged asset over decades, participating whole life offers both.

Business owners and incorporated professionals. A participating whole life policy held inside a corporation may offer a tax-efficient approach to building cash value inside a permanent policy, depending on the structure and the corporation’s specific situation. It can be used by incorporated professionals – such as dentists and physicians – to redirect excess corporate cash into a long-term, protected asset.

Estate planning. For those who want to leave a specific, guaranteed sum to their heirs or a charitable organization, a participating whole life policy creates a known outcome – the death benefit- regardless of when death occurs.

High net worth individuals. When other registered accounts (TFSA, RRSP) are maximized, participating whole life can offer a tax-efficient way to build cash value inside a permanent policy, outside of registered limits.

How It Fits Alongside Term Insurance

Term and participating whole life insurance are not competitors- they serve different purposes, and many Canadians use both at different stages of life.

Term insurance is a straightforward, affordable way to protect your family during the years it matters most – while a mortgage is being paid down, while children are young, or while income replacement is the primary concern. It does exactly what it is designed to do.


Participating whole life steps in when the need for coverage is permanent, when building long-term cash value matters, or when the policy is part of a broader estate or corporate strategy. The two products often complement each other well, and choosing one does not mean ruling out the other.

What to Take Away

Participating whole life insurance combines permanent death benefit protection with a growing cash value and the potential for dividends. It is a longer-term commitment with higher premiums, and it is designed for situations where permanence, cash value, and legacy planning are part of the picture.

If you are considering permanent life insurance, take time to review how dividend performance has held up at the insurer you are looking at, understand the various dividend options, and think through whether the long-term commitment fits your situation.

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such. Policy design, dividend scale performance, cash value growth, and tax treatment vary by insurer and by the specific policy contract. Always review the policy illustration and contract terms carefully.

Sources:

Participating Life Insurance – CLHIA