Critical Illness Insurance Explained

Critical Illness Insurance Explained

Why consider Critical Illness Insurance?

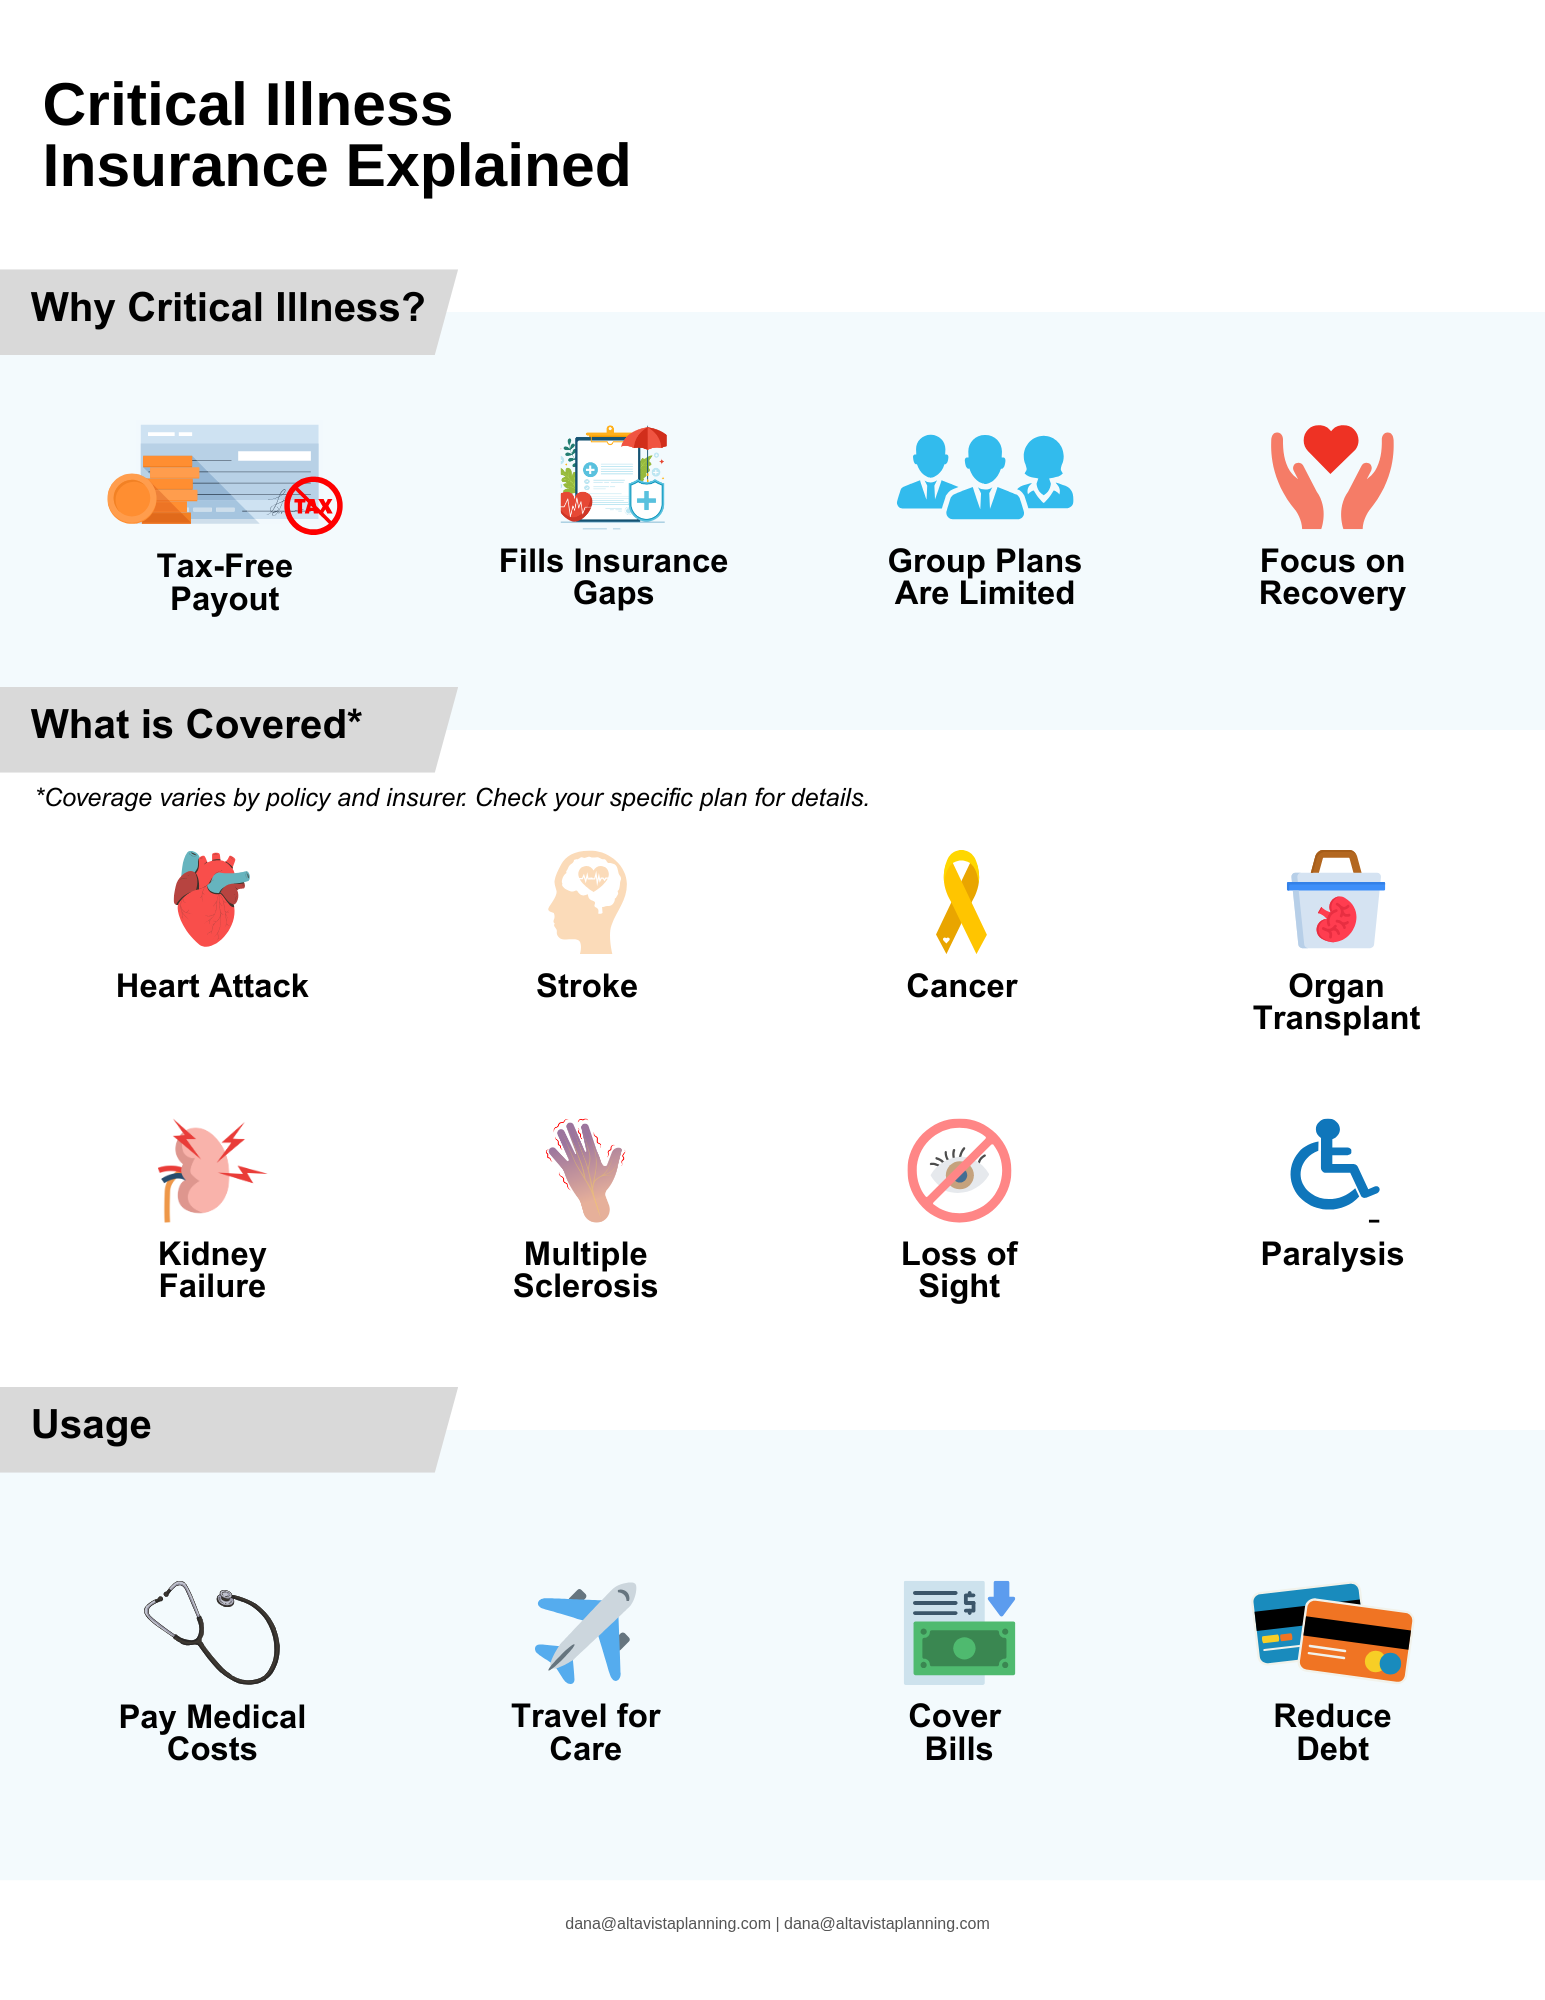
The purpose of Critical Illness Insurance is to provide a tax-free lump sum benefit if you’re diagnosed with a covered serious illness. It’s designed to ease the financial pressure that often comes with time away from work, medical costs not covered by government plans, and other unexpected expenses — so you can focus on your recovery, not your finances.

Even if you already have life insurance or workplace benefits, Critical Illness Insurance offers unique protection. Group plans often include only small amounts of coverage, may end if you leave your job, and usually don’t let you choose the benefit amount. A personal policy stays with you and can be tailored to your needs.

What does it cover?

Critical Illness Insurance pays out if you’re diagnosed with one of the serious medical conditions listed in your policy. These commonly include:

  • Cancer
  • Heart attack
  • Stroke
  • Major organ transplant
  • Kidney failure
  • Multiple sclerosis
  • Paralysis, loss of sight, hearing, or limbs
  • Alzheimer’s, Parkinson’s, motor neuron disease
  • Severe burns, benign brain tumour, aortic surgery

Some policies also provide partial payments for early-stage diagnoses. Your advisor can explain the specific definitions and conditions covered by your plan.

What types of policies are available?

Critical Illness Insurance is available in several forms, so you can choose the one that fits your needs and budget. The most common types include:

  • Term policies: Coverage for a fixed period, such as 10, 20, or 25 years.
  • Permanent policies: Coverage that lasts for life, as long as you pay the premiums.
  • Return of premium policies: Refund some or all premiums if no claim is made.
  • Group plans through an employer: Limited and usually not portable.

Is there a waiting period?

Yes — most policies include a short waiting period after diagnosis, usually 30 days, before the benefit is paid.
brandableContent

What factors affect the cost of Critical Illness Insurance?

The premium you pay for Critical Illness Insurance is influenced by both your personal situation and the policy you select. Understanding these factors can help you plan your coverage effectively:

  • Age: Younger applicants generally pay lower premiums, since the risk of serious illness increases with age.
  • Health history: Your medical history, as well as your family history, may lead to higher premiums or exclusions if there are risk factors.
  • Gender: Rates can differ slightly between men and women because of different incidence rates for certain conditions.
  • Smoking status: Smokers face higher premiums because of significantly greater risks of illnesses like cancer, heart disease, and stroke.
  • Lifestyle and occupation: Risky hobbies or high-stress, physically demanding jobs can also impact your cost.
  • Coverage amount: The larger the lump sum benefit you choose, the higher your premium.
  • Policy term: Permanent policies tend to cost more than term policies with fixed durations.
  • Optional riders: Adding features such as return of premium, premium waivers, or child coverage increases your premium.

By working with an advisor, you can balance these factors and find a policy that gives you the right level of protection at a price you’re comfortable with.

Are the benefits taxable?

No — in Canada, Critical Illness Insurance pays a tax-free lump sum benefit you can use however you wish.

How can you use the money?

The benefit is completely flexible. Many use it to:

  • Cover household expenses while off work
  • Pay for medications or private care
  • Reduce debts
  • Compensate a caregiver’s lost income
  • Travel for specialized treatment

When is the best time to purchase?

The best time to purchase Critical Illness Insurance is when you’re younger and healthy, so you qualify more easily and pay lower premiums.

How does Critical Illness Insurance fit into your insurance plan?

Most people already include life insurance in their plans to protect their family if they pass away. Many also rely on group disability insurance to replace part of their income if they can’t work due to illness or injury.

But Critical Illness Insurance is often overlooked — and that can leave a gap.

Life insurance only pays if you die, and disability insurance often replaces only a portion of your income, usually with limits and waiting periods. Neither addresses the immediate, unexpected costs of a serious illness, like out-of-pocket medical expenses, travel for treatment, hiring help at home, or paying off debts quickly.

Critical Illness Insurance fills this gap by providing a lump sum, tax-free benefit right after diagnosis, even if you’re still able to work. It complements your life and disability insurance to give you and your family a more complete, well-rounded safety net.

It’s worth reviewing your overall plan to make sure all three pieces — life, disability, and critical illness — are working together to protect your family and your lifestyle no matter what happens.

Critical Illness Insurance provides financial security during one of life’s most challenging times. It’s flexible, tax-free, and tailored to your needs — giving you and your family confidence that you’ll have support if the unexpected happens.

If you’d like help exploring your options or getting a personalized quote, reach out anytime.

Corporate Life Insurance Planning

Corporate Life Insurance Planning: Protect, Reward, and Plan for the Future

Running a business in often means wearing multiple hats—owner, leader, and long-term planner. But have you ever thought about what happens if you or a key person in your company passes away unexpectedly? Or how you might use your corporation to support retirement, reward top talent, or prepare for taxes when transitioning ownership?

Corporate life insurance is one of the most flexible and underused tools available to business owners. It helps protect your company, reduce taxes, and build lasting value—both during your working years and when it’s time to pass the business on.

Let’s look at how business owners are using corporate-owned life insurance to protect their companies and their families while preparing for the future.

brandableContent

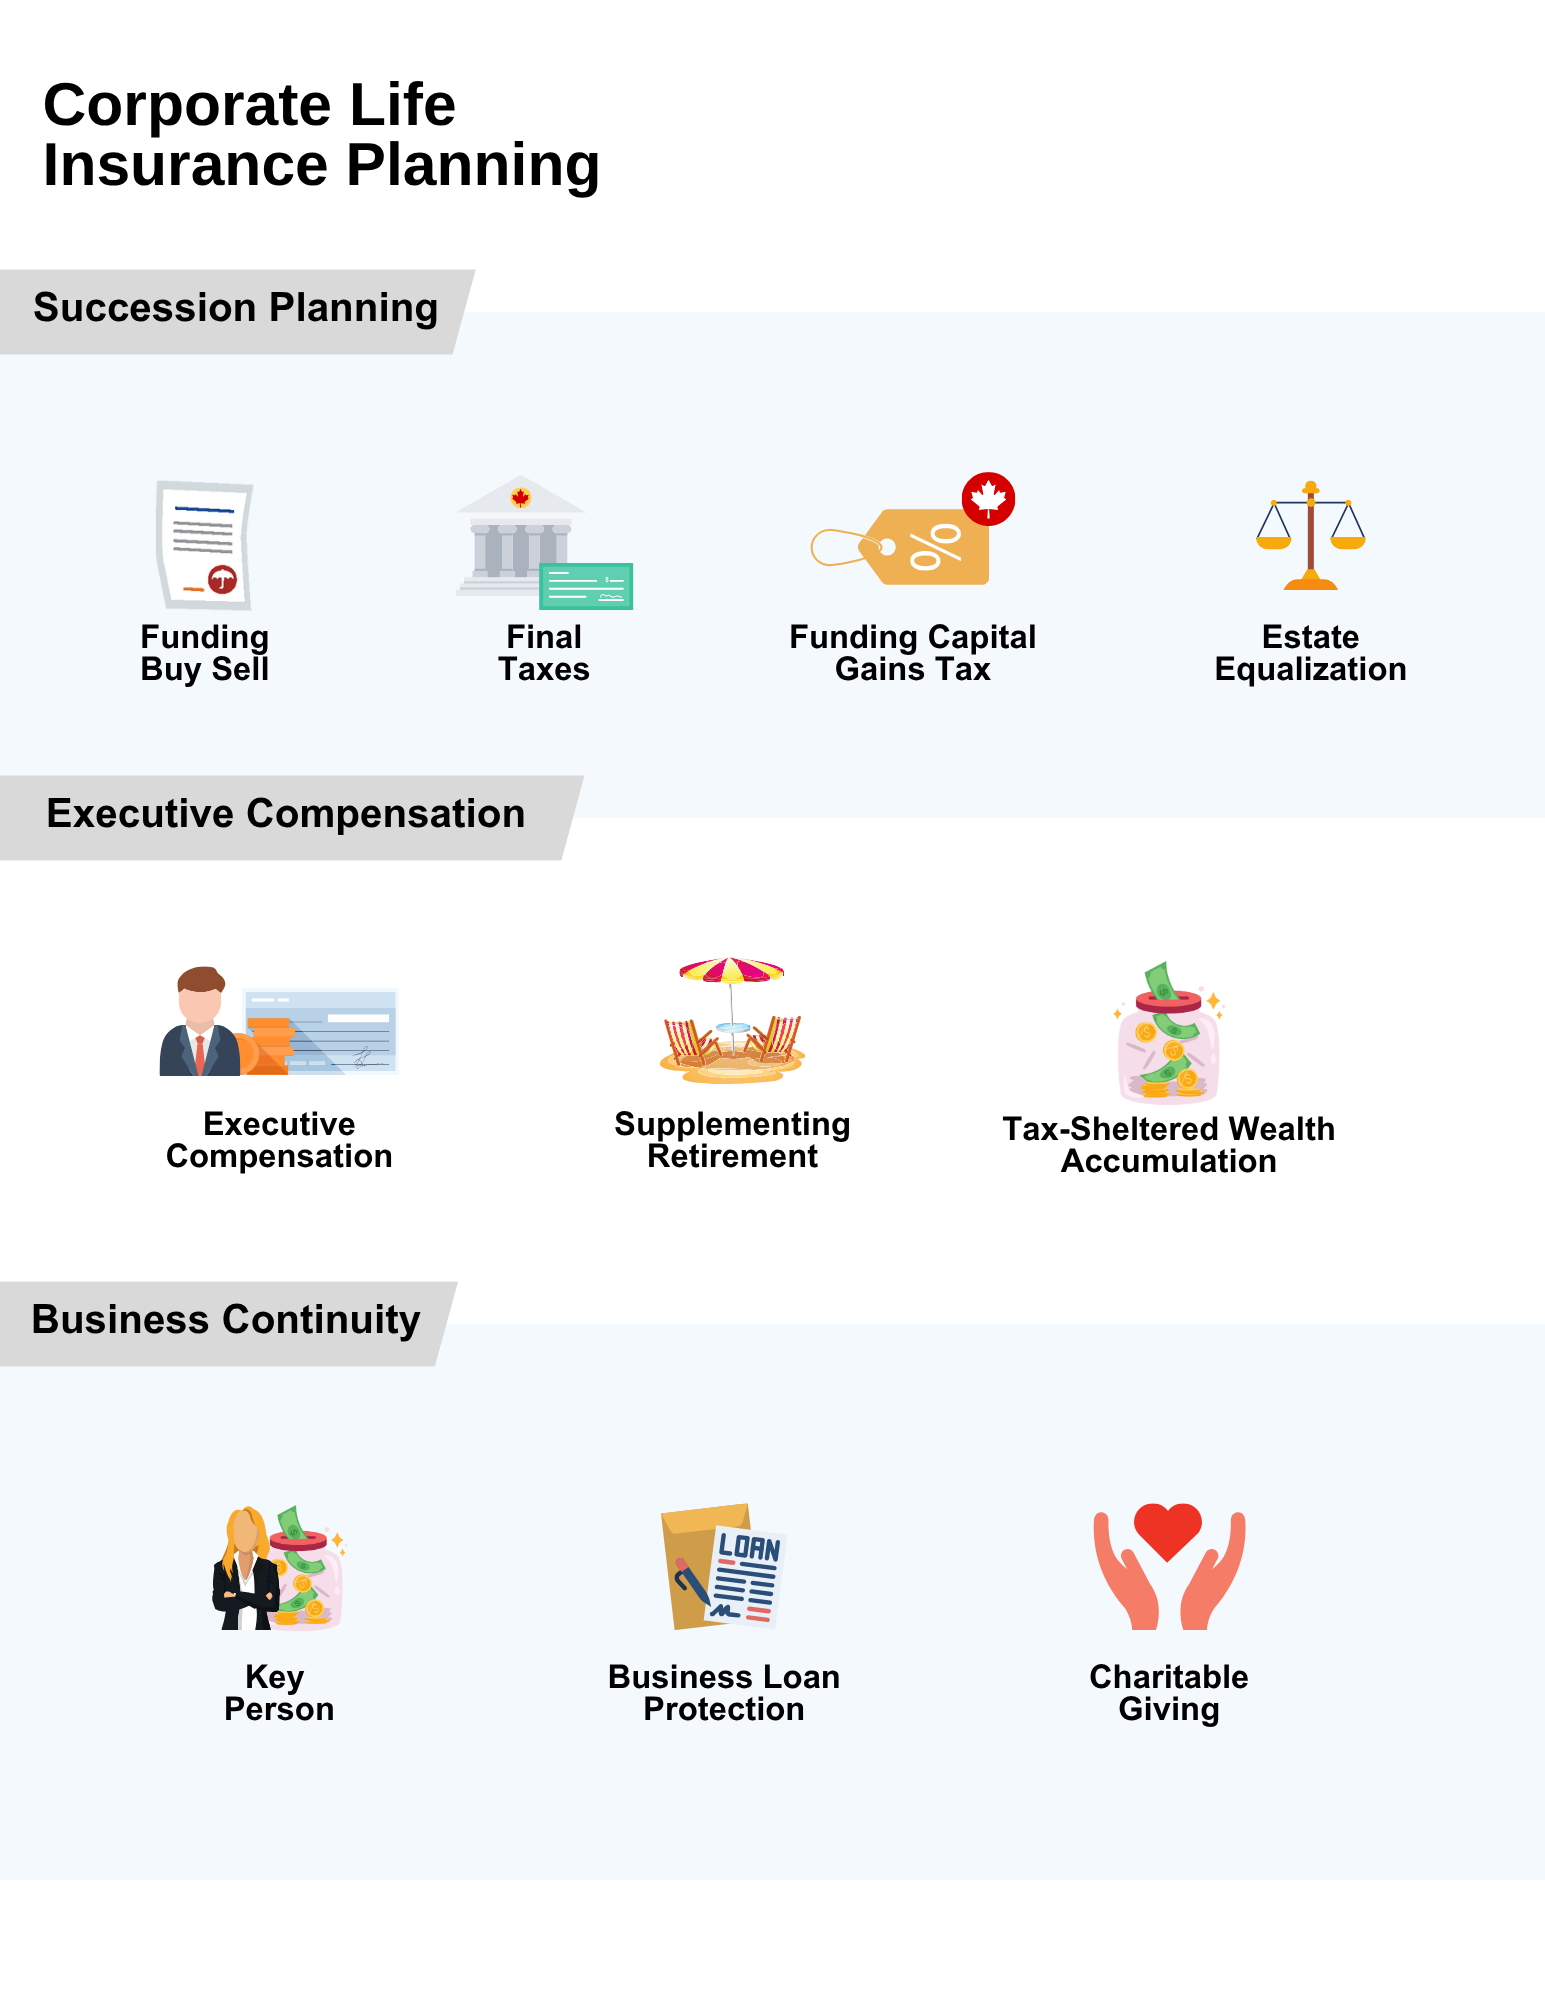
Succession Planning: Make Transitions Smooth and Tax-Smart

For many business owners, their company is one of their largest assets. But passing it on—whether to family or a partner—comes with major financial challenges. Life insurance can help.

Funding a Buy-Sell Agreement

If you have a business partner, a buy-sell agreement ensures that if one of you passes away, the other can buy the shares from the deceased’s estate. The problem? That buyout requires cash—often hundreds of thousands, if not millions. Life insurance is a cost-effective way to fund that agreement, so ownership stays in the right hands without putting a strain on the business or the family.

Covering Final Taxes and Capital Gains

When a business owner dies, the Canada Revenue Agency treats it as if they sold their shares—even if they didn’t. This “deemed disposition” creates a tax bill that can surprise even the most prepared families. Life insurance provides a tax-free lump sum that the corporation can use to cover this cost, helping preserve the value of the business and avoid selling off assets under pressure.

Estate Equalization

If you plan to leave the business to one child but want to treat your other children fairly, life insurance can help. The business goes to the child who’s involved, while other beneficiaries receive the life insurance proceeds. It’s a clean, tax-efficient way to avoid family conflict and keep the business whole.

Executive Compensation: Attract and Retain Top Talent

In a competitive hiring environment, offering the right benefits can make all the difference. Life insurance isn’t just about protection—it can be a powerful way to reward and retain your most valuable people.

Executive Compensation Strategies

Life insurance can be part of a compensation package that rewards top performers, especially those who are key to the company’s success. Whether structured as a bonus plan or part of a long-term incentive, this can be a powerful way to align goals and build loyalty.

Supplementing Retirement

Permanent life insurance policies—such as whole life or universal life—can accumulate cash value over time. This cash value grows tax-deferred and can later be accessed through policy loans or collateralized lending. For business owners and executives, this provides an additional, flexible income source in retirement, especially when RRSP and TFSA contribution limits have already been reached. It allows the corporation to efficiently use surplus cash while providing long-term financial flexibility and security.

Tax-Sheltered Wealth Accumulation

The cash value inside a permanent life insurance policy grows on a tax-deferred basis. When a corporation owns the policy, this growth can be especially strategic. It allows the business to use surplus cash to build value in a tax-efficient way, diversify beyond traditional investments, and potentially access funds later with fewer tax consequences. This approach is particularly useful for businesses with retained earnings that would otherwise be subject to higher corporate tax rates.

Business Continuity: Protect What You’ve Built

An unexpected death can do more than cause emotional pain—it can disrupt operations, shake client confidence, and even put the business at risk. Insurance helps ensure your company can keep going.

Key Person Protection

If you or someone else is essential to the day-to-day success of your business, losing that person could be a major financial blow. A life insurance policy on that individual can help the business recover, cover short-term losses, and fund the search for a replacement.

Business Loan Protection

Many lenders require insurance on owners or key executives as a condition of financing. If that person passes away, life insurance ensures the loan is paid off, protecting both the lender and the company’s assets. It can also unlock better lending terms and help avoid personal guarantees.

Charitable Giving Through the Corporation

For business owners looking to give back, corporate life insurance can also be used to support charitable causes. The business can own a policy and name a charity as the beneficiary—creating a lasting impact while offering potential tax benefits.

Bringing It All Together

Corporate life insurance isn’t just about “what if”—it’s about building a stronger, more resilient business and unlocking smart ways to manage wealth inside your company. Whether you’re focused on succession, rewarding your team, or protecting operations, insurance can help you take action today that pays off for years to come.

If you haven’t reviewed your corporate insurance strategy recently, now’s a great time to take a fresh look.

Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.

Financial Checklist for New Parents in Canada

What to Do Financially When You Have a Baby

A new baby brings a lot of joy, and a lot of new to-do lists. Most of them are about feeding schedules and car seats. But a few items on the list are about money, and they matter more than you might think.

You do not need to do everything at once. A newborn keeps you busy enough. The steps below can be spread out over the first few months. Think of this as a simple checklist you can come back to as you find the time and energy.

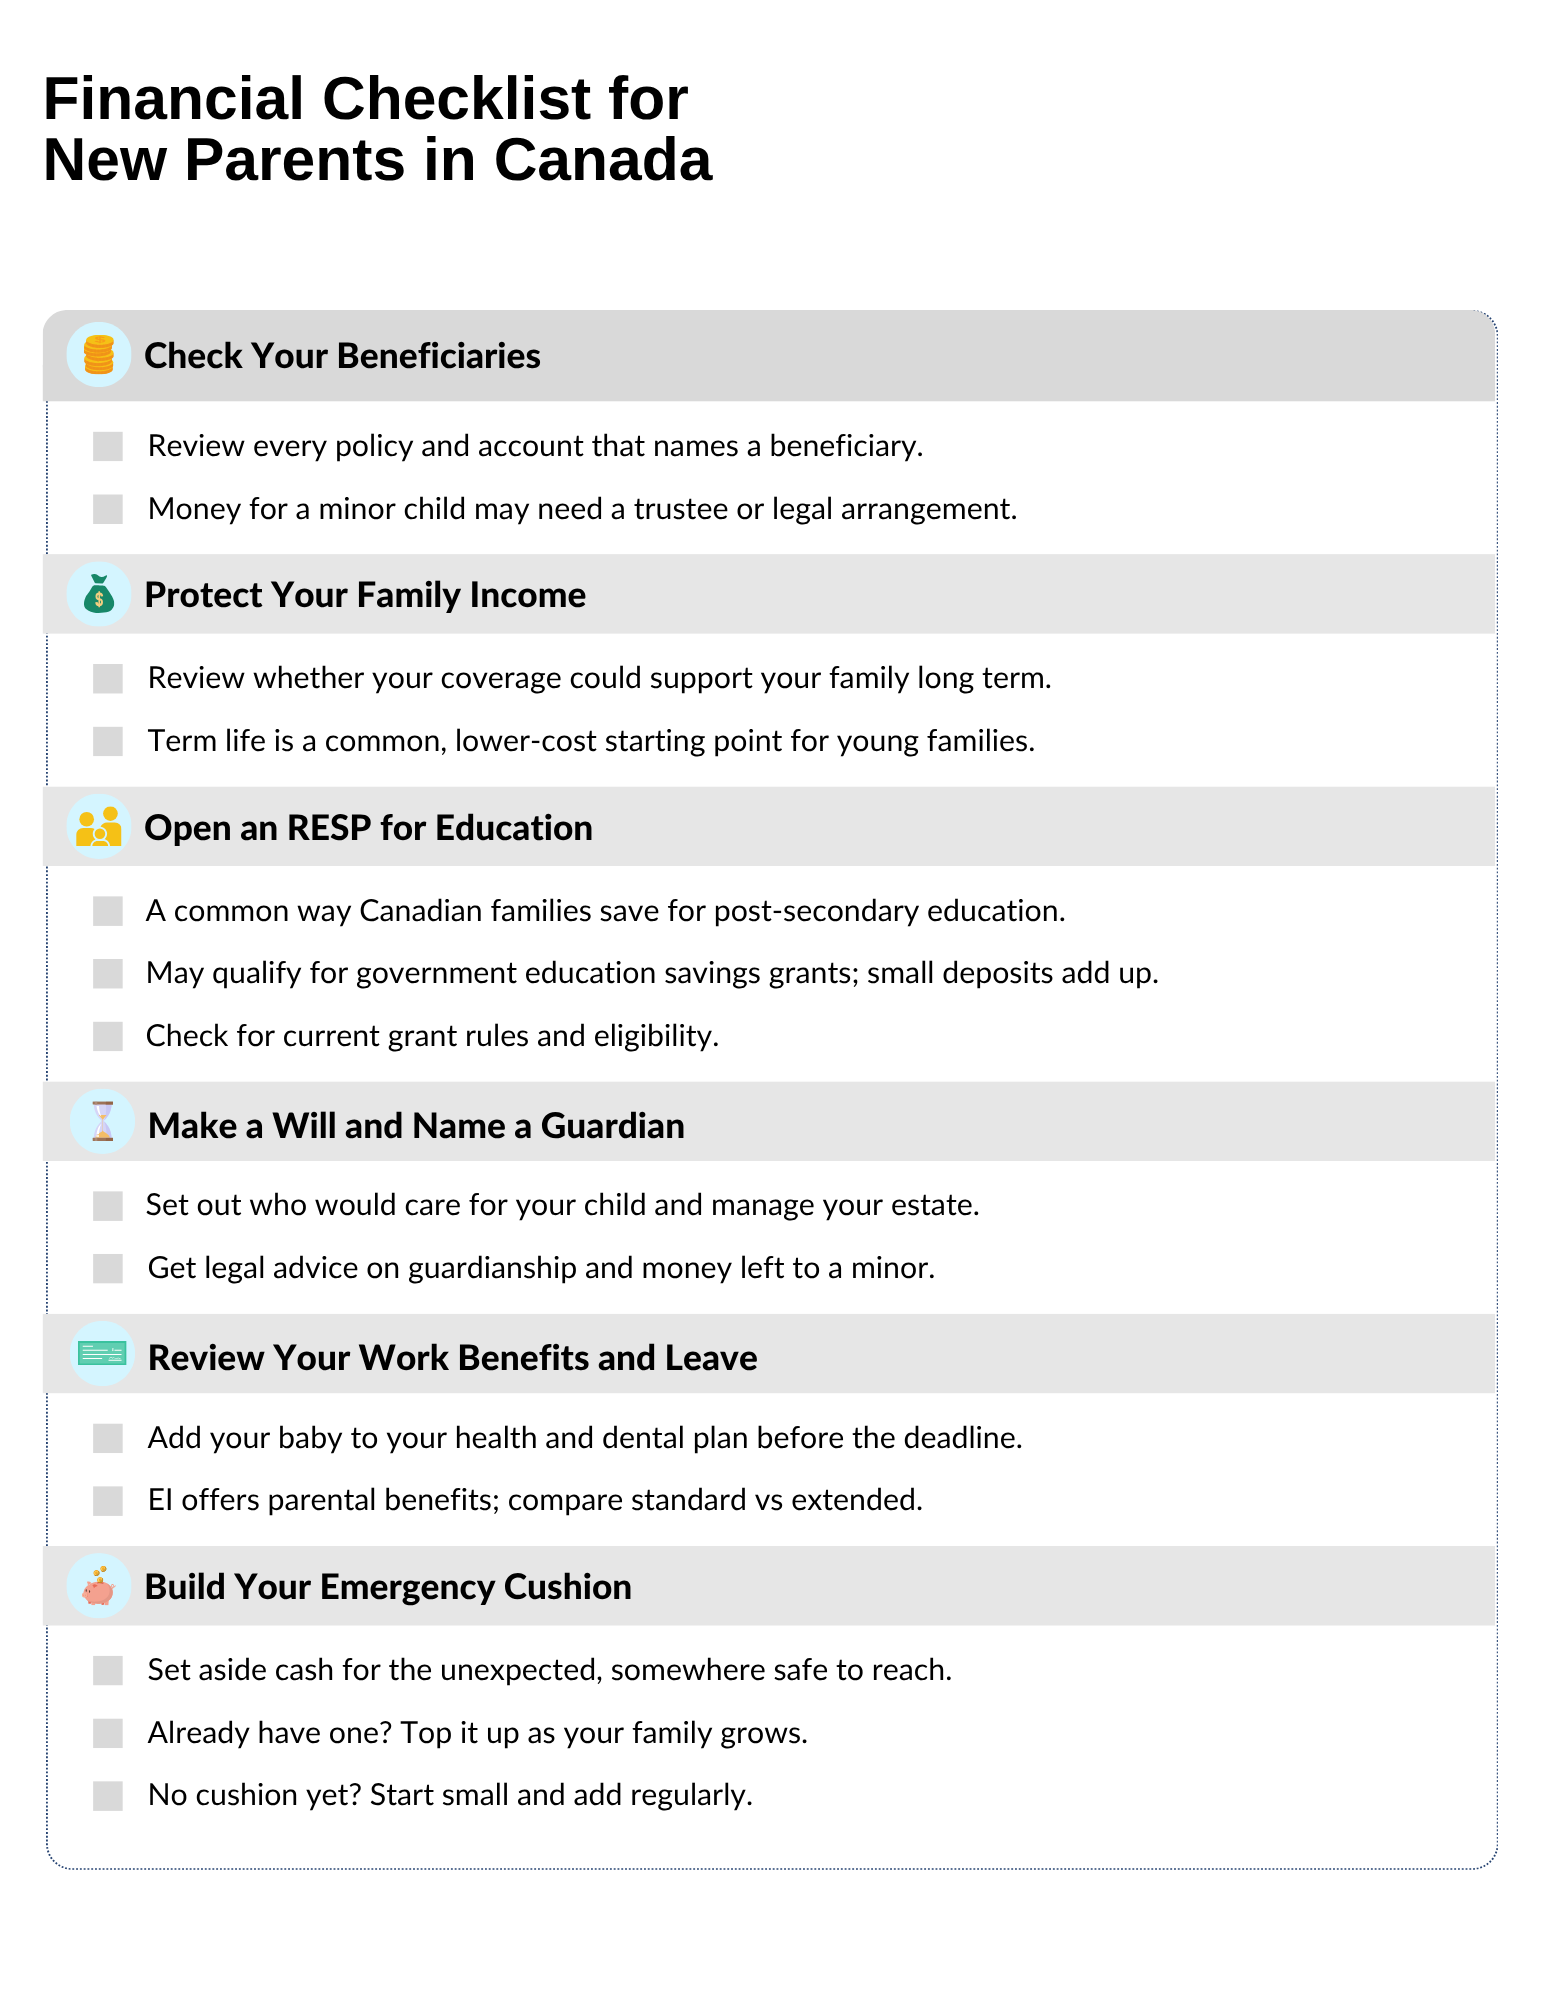
Check Your Beneficiaries

A beneficiary is the person who receives the money from your life insurance or certain registered accounts after you pass away. Many people set these up years ago and never look at them again.

Now is a good time to check. You may want to add your partner, update an older choice, or think through how money should be handled for your child. If you want money to go to a minor child, it may need to be managed through a trustee or other legal arrangement until the child is of age, depending on the asset and the province.

The key point is simple. Look at every policy and account that names a beneficiary, and make sure the names and instructions still match the life you have today.

Protect Your Family Income With Life Insurance

When it was just you, or just you and your partner, a gap in income may have been easier to manage. With a baby who depends on you, the stakes are higher. Life insurance can help protect your family financially if something happens to you, so they can keep up with housing costs, bills, and daily expenses.

For many young families, term life insurance is a common starting point. It covers you for a set number of years, often when your children are young and your financial obligations are highest. The premiums are usually lower than permanent coverage, which can make it easier to fit into a new-parent budget.

Your need for coverage often increases when you have a child. It is worth checking whether your current coverage, including any through work, would be enough to support your family for more than just the short term.

brandableContent

Open an RESP for Education

A Registered Education Savings Plan, or RESP, is a common way Canadian families save for a child’s post-secondary education. One reason many parents use it is the government support that can come with it through education savings grants.

You do not need a large amount to begin. Even small, regular deposits can add up over time. Check canada.ca for the current grant rules, contribution details, and eligibility requirements.

Make a Will and Name a Guardian

This is the step many new parents put off, and it is one of the most important. A will helps set out who would care for your child and how your estate should be handled if you and your partner die.

For parents, the most important part is often naming the person you want to care for your child. In BC, a will can express your wishes about guardianship, but it is also important to work with proper legal advice so your will deals clearly with both the care of your child and the management of any money left to a minor.

If you already have a will, a new baby is a good reason to review it. Add your child, confirm your choices, and make sure your estate plan still reflects your wishes.

Review Your Work Benefits and Leave

Your job may offer more help than you realize. Many group benefit plans allow you to add a new dependent, but the deadline depends on the plan. Check with your human resources team or plan administrator as soon as possible after the birth so you do not miss the deadline for health and dental coverage.

Employment Insurance, or EI, also offers maternity and parental benefits for eligible parents. Parents can choose standard or extended parental benefits, and the timing and number of weeks differ between the two options, so it is important to review the current rules before applying.

Build Your Emergency Cushion

A baby comes with surprises, and some of them cost money. An emergency cushion is simply cash set aside for the unexpected, kept somewhere safe and easy to reach.

If you already have one, this is a good time to top it up. A larger family often means larger surprise costs. If you do not have one yet, start small. Even a modest amount set aside regularly can help keep a rough week from becoming a money crisis.

A Calm Way to Start

That is a full list, and you do not have to tackle it all at once. Pick one item this week. Maybe it is checking a beneficiary, or asking work about adding your baby to your benefits. Small steps, taken one at a time, can help build a stronger financial foundation for your growing family.

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

Sources:

Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?

Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?

If drug costs have been climbing on your group benefits plan, GLP-1 medications like Ozempic are likely part of the reason. These drugs have been among the fastest-growing cost drivers in employer-sponsored plans across the country. So when Health Canada approved a generic version of semaglutide, the active ingredient in Ozempic, on April 28, 2026, and a second generic followed in early May, it was welcome news for anyone managing a group drug plan. Canada was the first G7 country to approve a generic semaglutide.

But here is the thing: lower costs are not guaranteed just because a cheaper version of the drug exists. Whether your plan actually sees savings depends almost entirely on how it is designed.

What Happens When a Drug Goes Generic?

When a brand-name drug loses patent protection, other manufacturers can produce and sell equivalent versions at a lower cost. The savings can be significant.

As a rule of thumb in the industry, when one or two generics enter the market, prices may fall by 20 to 30 per cent below the brand-name drug. With more generics competing over time, those discounts can deepen further. These are general industry estimates, and actual outcomes will vary.

For Ozempic specifically, this could translate to roughly one to two per cent savings on a plan’s total drug costs. That may sound modest, but for organizations with meaningful Ozempic spend, it adds up quickly, especially at renewal.

Why Savings Do Not Happen Automatically

Here is where many plan sponsors get caught off guard: the existence of a generic does not mean your plan will automatically pay for it at the lower price.

Without specific plan design provisions in place, many members may stay on the brand-name drug. Their doctor prescribed it. They have been taking it. They may not even know a generic exists. And if your plan covers it without any substitution requirement, there is little reason to switch.

The result is a plan that may continue paying brand-name prices for a drug that now has a lower-cost equivalent on the market.

What Plan Sponsors Can Do Right Now

The arrival of generic Ozempic creates a real window to act, but it requires a conversation with us. Here are the three areas worth reviewing:

Generic substitution policies. Many plans already have mandatory substitution clauses that require members to use a generic when one is available, unless there is a medical reason not to. If your plan does not have this in place, or if it only applies to certain drug categories, now is the time to review it. Adding generic substitution for GLP-1 medications could meaningfully reduce what the plan pays.

Prior authorization requirements. Prior authorization means a member needs approval before the plan will cover a specific drug. This is particularly useful for high-cost medications where clinical criteria should be confirmed before coverage is granted. It also creates a natural point to direct members to the generic option. If your plan does not currently require prior authorization for GLP-1 medications, that is worth exploring with your insurer.

Brand-name pricing negotiations. In some cases, insurers may be able to negotiate pricing directly with brand-name drug manufacturers. This is not a standard plan-design feature, but it is worth asking your insurer whether it is an option and whether brand-name semaglutide pricing is available through their arrangements. If it is available, it could help reduce costs even for members who remain on the brand-name drug for medical reasons.

The Bigger Picture on Plan Design

Generic Ozempic is a useful reminder that drug plan management is not a set-it-and-forget-it exercise. Small design decisions, like whether a plan has a substitution clause or a prior authorization requirement for high-cost drugs, can translate into real, measurable differences in cost over time.

For organizations that have seen drug costs climb in recent years, this is a meaningful opportunity. The savings potential is real. Whether your plan captures it depends on reviewing your plan design and having a conversation with us before your next renewal.

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

Sources:

What Happens to Your Group Benefits When You Leave a Job?

What Happens to Your Group Benefits When You Leave a Job?

Leaving a job, whether by choice or by circumstance, brings a long to-do list. Updating your resume, signing new paperwork, figuring out your finances. One item that often gets missed in the shuffle: your group benefits.

For many Canadians, employer-provided health, dental, vision, and life insurance coverage quietly disappears the moment they leave. Here is what actually happens, what your options are, and what steps to take so you do not end up without coverage when you need it most.

When Does Coverage End?

The exact end date depends on your employer’s plan, but most group benefits plans terminate coverage on one of two dates:

  • The last day of active employment, meaning your coverage ends the day you stop working.

  • The last day of the month in which you stop working, which gives you a short buffer.

Your employee handbook or HR contact can confirm which applies to your plan. If you are being laid off or terminated, sometimes an employer will extend benefits for a defined period as part of a severance arrangement, this should be spelled out in any severance agreement you receive. In some provinces, such as British Columbia, employees who are laid off may also have the option to voluntarily continue their coverage for up to six months by paying the premiums themselves.

The takeaway: do not assume coverage continues past your last day. It usually does not, and even a brief gap can leave you on the hook for expenses.

brandableContent

What Coverage Goes With You, and What Disappears

Not all group benefits disappear the same way. Here is what typically happens with each type:

Health and dental: These end on your termination date (or end of month, depending on the plan). Most plans include a run-off period, typically 30 to 90 days, to submit claims for services you received while you were still covered. Any claims for services after your termination date will be denied. Before you leave, it is worth getting any outstanding treatments done and filling any prescriptions. Some insurers also offer conversion options for extended health and dental coverage within 60 to 90 days of losing group coverage, though this is less common than life insurance conversion.

Vision: Same as health and dental, coverage ends, and unused benefit maximums do not transfer.

Life insurance and accidental death and dismemberment (AD&D): Group life insurance through your employer is usually converted to an individual policy without medical evidence through a feature called the conversion privilege. This is one of the most important and least-known options available to departing employees.

Short-term and long-term disability: These stop when employment ends. You cannot claim disability benefits from a former employer’s plan after your last day. If you are already on a disability claim when you leave, the rules get more specific, check your plan documents.

Employee Assistance Programs: These end at termination as well.

The Conversion Privilege: A Rarely Used but Valuable Option

Most group life insurance plans come with a conversion privilege, the right to convert your group life coverage to an individual permanent life insurance policy without providing evidence of insurability. That means no medical questions, no physical exam.

There is a catch: you typically have only 31 days from the date your group coverage ends to exercise this option. Miss that window, and you lose it.

The converted policy will cost more than your group coverage did. Group rates are typically lower because the risk is pooled across all employees. An individual policy reflects your age and the fact that the insurer cannot screen for health. But for someone who has developed a health condition during employment and would otherwise have difficulty qualifying for individual coverage, this option is a lifeline.

Contact your former employer’s benefits administrator or the insurer directly to find out the exact deadline and how to start the conversion process.

Your Options for Replacing Health and Dental Coverage

Once your group plan ends, you have a few paths to replacing health and dental coverage:

A spouse or partner’s plan. If your partner has their own employer plan, losing your group coverage is typically considered a qualifying life event that allows them to add you immediately, without waiting for an open enrollment period. Act within 30 to 60 days of your coverage ending, as most plans require prompt notification.

Individual health and dental insurance. Insurance companies offer individual health and dental plans that you can apply for on your own. Premiums are higher than group rates, and pre-existing conditions may not be covered, but this option fills the gap if no group plan is available to you. Many providers allow applications within 60 days of losing group coverage to waive certain waiting periods.

Professional or industry associations. Some professional groups, engineers, teachers, freelancers, offer group benefit plans to members at better rates than individual plans. If you belong to or qualify for membership in an association, this can be worth exploring.

What to Do Before Your Last Day

A few practical steps to take before you walk out the door:

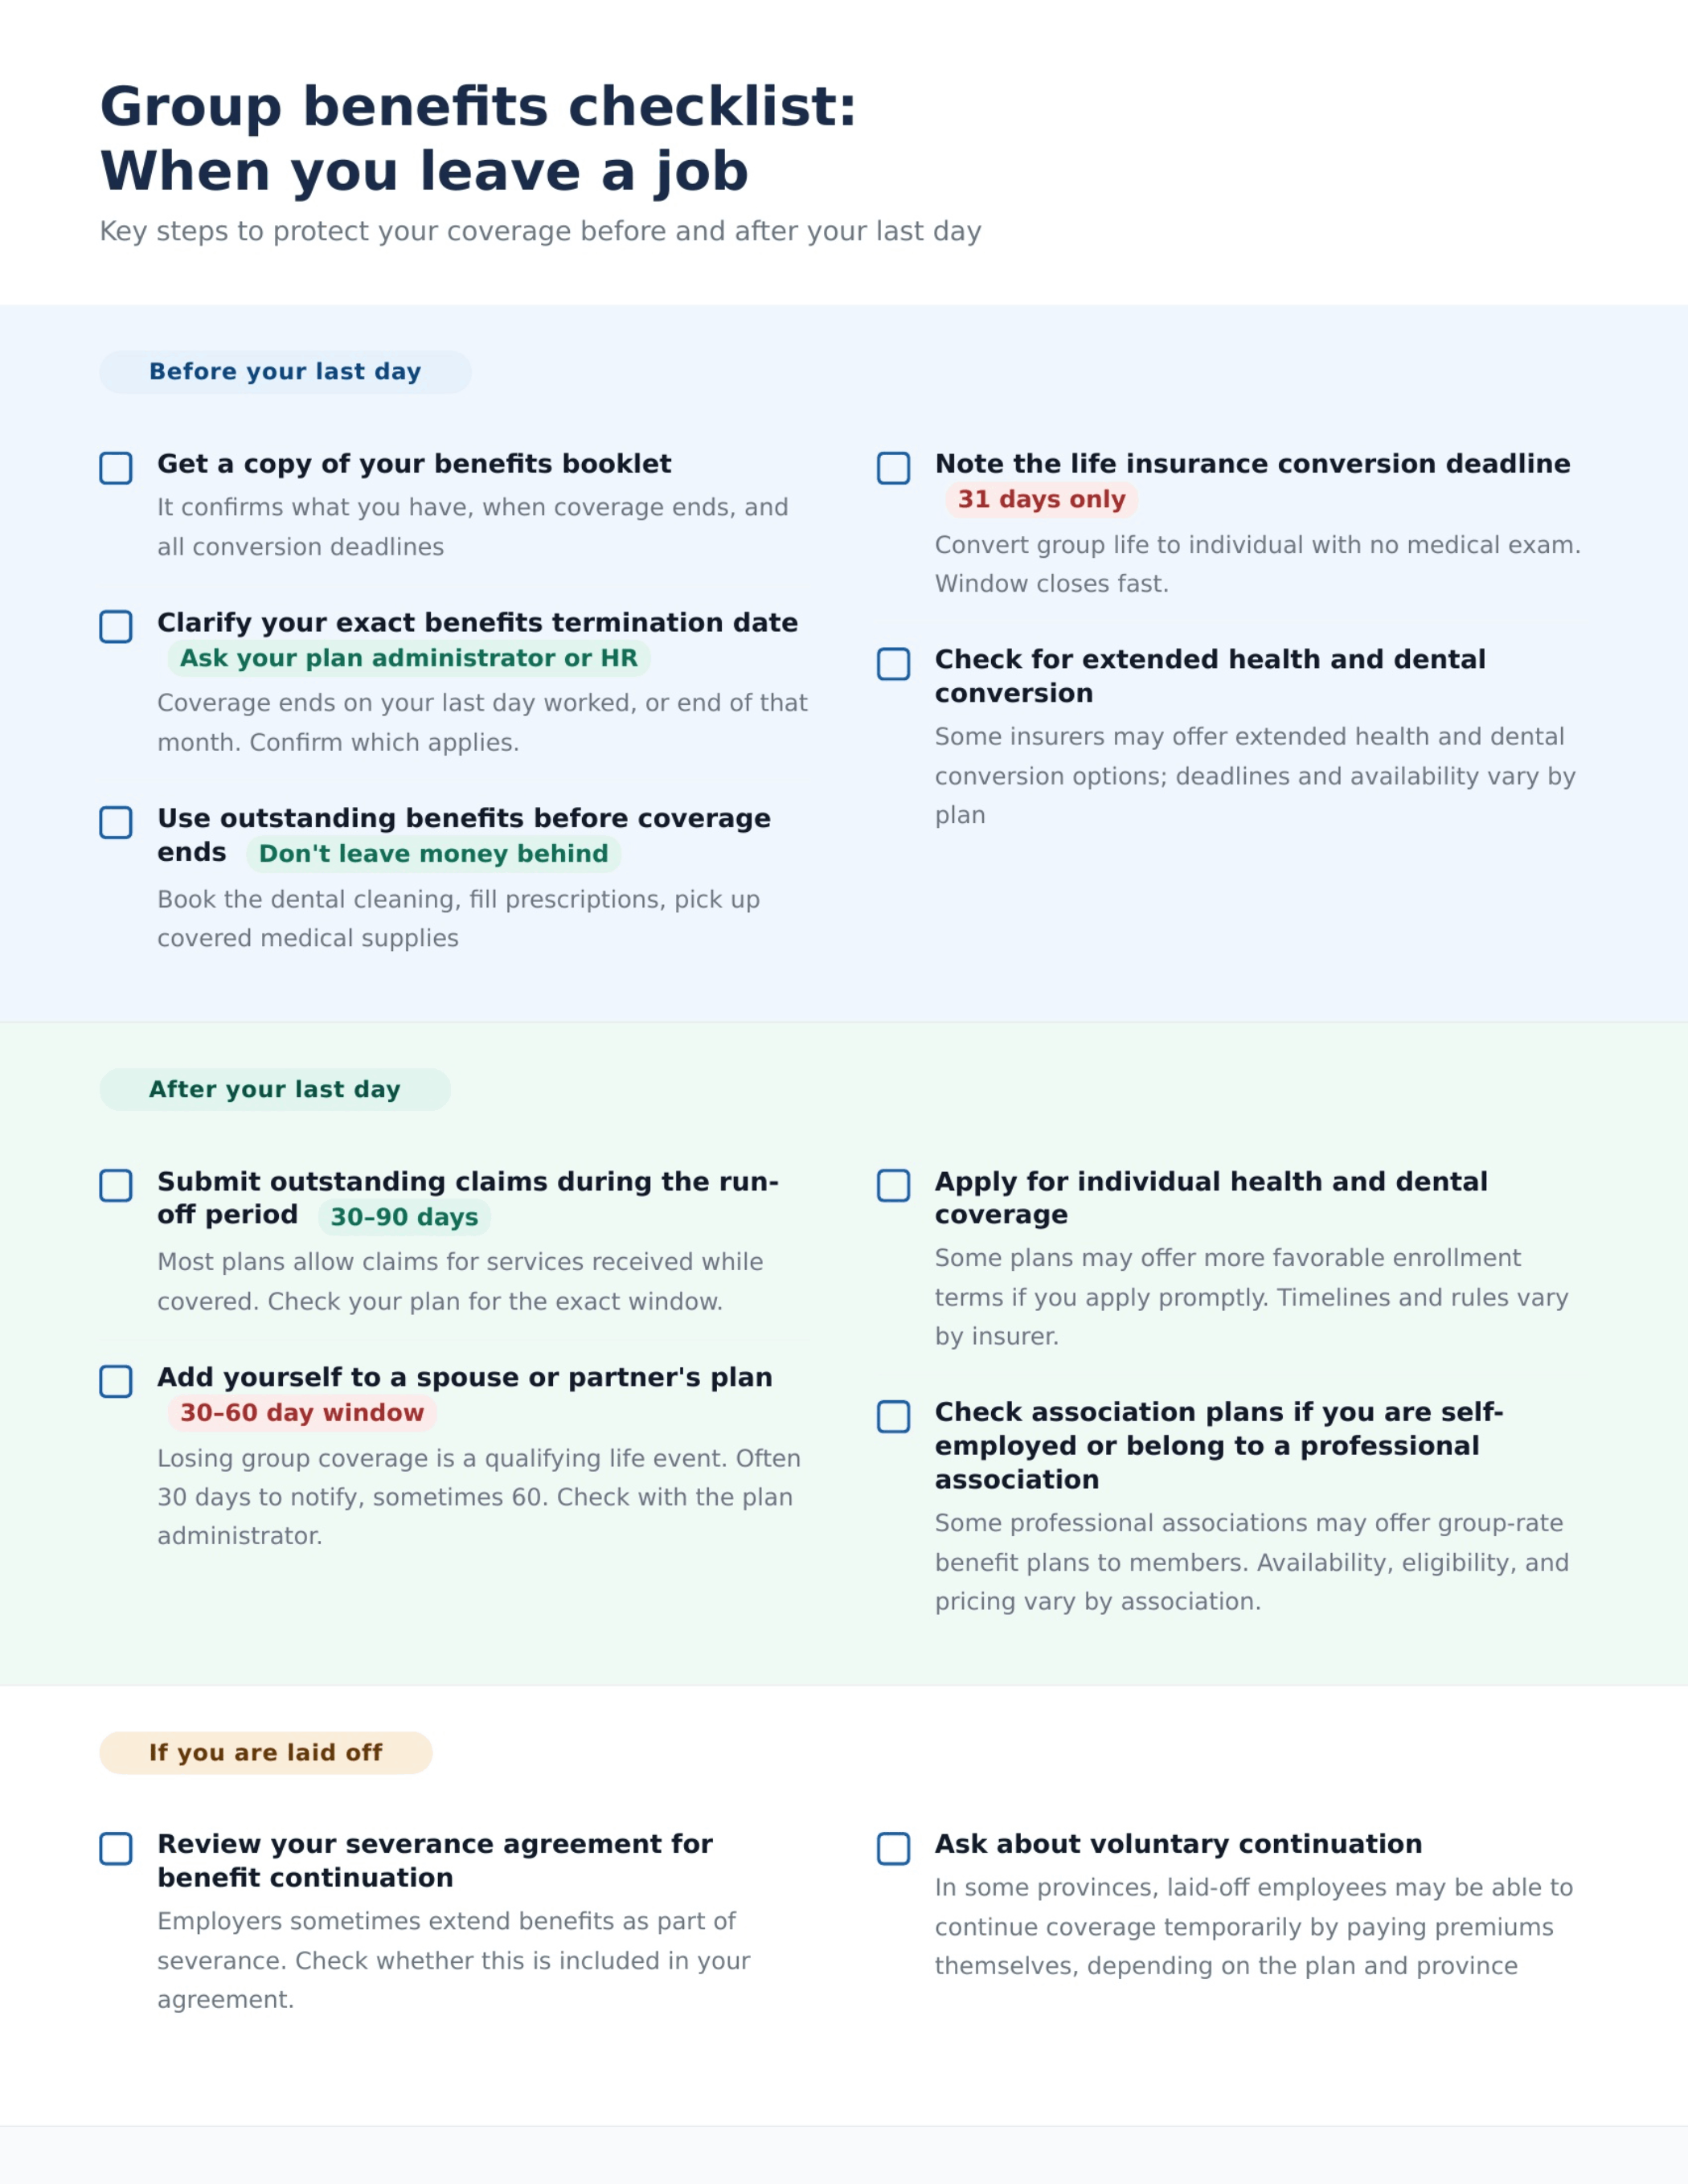
Get a copy of your benefits booklet or summary plan document. This outlines exactly what your plan covers, how conversion works, and the deadlines involved. HR should be able to provide this.

Use what you can before your coverage ends. Book that dental cleaning, fill outstanding prescriptions, and pick up any medical supplies covered under your plan. Most people leave money on the table simply by not timing this properly.

Clarify your exact termination date for benefits purposes. Ask HR explicitly whether benefits end on your last day worked or at the end of that month.

Check the conversion privilege deadline. If you have any concern about qualifying for individual life insurance, find out your deadline immediately and do not let it pass.

Notify your partner’s employer. If you plan to join your partner’s group plan, they need to notify their plan administrator within the required window, typically 30 to 60 days.

The Gap You Do Not Want

Going without health and dental coverage for even a short time can be expensive. A single dental emergency, a course of prescription medication, or a specialist visit that falls outside provincial coverage can cost hundreds to thousands of dollars out of pocket.

The good news is that a gap does not have to happen. With a bit of planning and quick action after your last day, you can move from one source of coverage to another without interruption.

Have questions about your coverage options? We are here to help. Reach out to our team and we will walk you through what makes sense for your situation.

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

Sources:

What Is Participating Whole Life Insurance?

What Is Participating Whole Life Insurance?

Most people buy life insurance for one reason: to make sure their family is protected if something happens to them. But there is a type of life insurance that does something more – it builds value over time while you are still alive. That type is called participating whole life insurance, and it works very differently from the term policies most Canadians are familiar with.

Here is what it means, how it works, and whether it might be a fit for you.

Permanent Coverage That Does Not Expire

Term life insurance covers you for a set period – 10, 20, or 30 years. Participating whole life insurance is permanent. It covers you for your entire life, as long as premiums are paid, and the death benefit is guaranteed.

That permanence is the first major difference. But the bigger difference is what happens to your premiums while you are alive.

With a term policy, your premiums go entirely toward the cost of insurance. With participating whole life, the insurer pools premiums into a participating account that is professionally managed. Dividends may be paid when the account’s experience is favourable, based on factors such as investment returns, expenses, and mortality experience.

How Dividends Work

The word “dividend” here is different from stock dividends. In the context of a participating whole life policy, a dividend is a share of the insurance company’s surplus – essentially, the company returning a portion of the money when investment performance, claims experience, and expenses go better than expected.

These dividends are not guaranteed. They are declared each year by the insurance company based on how the participating account performed. That said, many Canadian participating insurers have long histories of paying dividends, though past performance does not guarantee future results.

When you receive a dividend, you have a few options for how to use it:

  • Take it as cash. The dividend is paid to you directly.

  • Apply it to your premium. It reduces how much you pay out of pocket.

  • Buy additional paid-up insurance. This is the most common choice. The dividend purchases more coverage, which in turn earns its own dividends. Over time, this compounds.

  • Leave it on deposit. The dividend sits with the insurer and earns interest.

Most policyholders who hold participating whole life for the long term choose to purchase additional paid-up insurance, because it accelerates both the death benefit and the cash value of the policy.

The Cash Value

One of the most distinctive features of a participating whole life policy is that it builds cash value. The policy builds guaranteed cash value as part of its structure, and dividends can add a non-guaranteed layer of growth if they are used to buy paid-up additions.

The policy accumulates cash value that you may be able to access, subject to policy terms, in a few ways:

  • Policy loans. You can borrow against the cash value without going through a lender or credit check. Policy loans do not have fixed repayment schedules, but any unpaid balance can reduce the death benefit.

  • Surrendering the policy. If you decide you no longer need the coverage, you can cancel the policy and receive the accumulated surrender value. The tax treatment on surrender can be technical and depends on the policy’s adjusted cost basis — the disclaimer at the end of this article applies here.

The cash value grows on a guaranteed basis, separate from the dividends. The dividends, if used to purchase paid-up additions, add a non-guaranteed layer of growth on top.

Who Is This Type of Policy For?

Participating whole life is not the right fit for every situation. Because premiums are higher than term insurance, it is most commonly used by people who have a long-term need for life insurance and who can sustain the premium over time.

Some of the most common situations where it makes sense:

Families building long-term wealth. For parents who want to ensure a guaranteed death benefit no matter when they pass, plus build a tax-advantaged asset over decades, participating whole life offers both.

Business owners and incorporated professionals. A participating whole life policy held inside a corporation may offer a tax-efficient approach to building cash value inside a permanent policy, depending on the structure and the corporation’s specific situation. It can be used by incorporated professionals – such as dentists and physicians – to redirect excess corporate cash into a long-term, protected asset.

Estate planning. For those who want to leave a specific, guaranteed sum to their heirs or a charitable organization, a participating whole life policy creates a known outcome – the death benefit- regardless of when death occurs.

High net worth individuals. When other registered accounts (TFSA, RRSP) are maximized, participating whole life can offer a tax-efficient way to build cash value inside a permanent policy, outside of registered limits.

How It Fits Alongside Term Insurance

Term and participating whole life insurance are not competitors- they serve different purposes, and many Canadians use both at different stages of life.

Term insurance is a straightforward, affordable way to protect your family during the years it matters most – while a mortgage is being paid down, while children are young, or while income replacement is the primary concern. It does exactly what it is designed to do.


Participating whole life steps in when the need for coverage is permanent, when building long-term cash value matters, or when the policy is part of a broader estate or corporate strategy. The two products often complement each other well, and choosing one does not mean ruling out the other.

What to Take Away

Participating whole life insurance combines permanent death benefit protection with a growing cash value and the potential for dividends. It is a longer-term commitment with higher premiums, and it is designed for situations where permanence, cash value, and legacy planning are part of the picture.

If you are considering permanent life insurance, take time to review how dividend performance has held up at the insurer you are looking at, understand the various dividend options, and think through whether the long-term commitment fits your situation.

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such. Policy design, dividend scale performance, cash value growth, and tax treatment vary by insurer and by the specific policy contract. Always review the policy illustration and contract terms carefully.

Sources:

Participating Life Insurance – CLHIA

What Is Life Insurance and How Does It Work?

What Is Life Insurance and How Does It Work?

Have you ever wondered what would happen to your family’s finances if you were no longer here? It’s not an easy thought. But it is an important one. Life insurance is designed to protect the people you care about most if something unexpected happens.

Many people avoid this topic because it feels uncomfortable or confusing. The good news is that life insurance is actually quite simple once you break it down.

What Is Life Insurance?

Life insurance is a contract between you and an insurance company. You pay a regular payment called a premium. In return, the insurance company agrees to pay a lump sum of money to someone you choose (your beneficiary) if you pass away.

That lump sum is called a death benefit. In most cases, it is paid tax-free to your beneficiary.

Think of life insurance like a safety net. You hope it is never needed. But if it is, it can help your family stay financially stable during a very difficult time.

Millions of Canadians have some form of life insurance coverage. For many families, it plays an important role in protecting income and covering large expenses.

How Does Life Insurance Work?

The process is straightforward.

First, you apply for coverage. The insurance company reviews details such as your age, health, lifestyle, and sometimes your occupation. This helps them decide your premium and whether you qualify.

Once approved, you begin paying premiums. As long as you keep paying, your coverage remains active.

If you pass away while the policy is active, your beneficiary files a claim. The insurance company reviews the claim and then pays out the death benefit.

Your beneficiary can use the money for any purpose, such as:

  • Paying off a mortgage

  • Covering funeral expenses

  • Replacing lost income

  • Paying off debt

  • Supporting children’s education

The goal is to reduce financial stress at a time when your family is already dealing with emotional loss.

The Two Main Types of Life Insurance

Most people choose between two main types of coverage: term life insurance and permanent life insurance.

Term Life Insurance

Term life insurance covers you for a set period of time, such as 10, 20, or 30 years.

It is usually the most affordable option, especially for young families. If you pass away during the term, the policy pays out. If the term ends and you are still living, the coverage ends unless you renew it.

Term insurance works well for temporary needs. For example:

  • Protecting your income while your children are young

  • Covering a mortgage while the balance is high

  • Replacing income during your working years

It is simple and focused on protection.

Permanent Life Insurance

Permanent life insurance covers you for your entire lifetime, as long as premiums are paid.

It also includes a savings feature called cash value. Over time, this value can grow on a tax-deferred basis.

Permanent coverage is usually more expensive than term coverage. However, it can support longer-term goals such as:

  • Covering final expenses

  • Leaving money to family or a charity

  • Helping manage taxes at death

  • Supporting estate planning goals

The right type of coverage depends on your needs, timeline, and budget.

How Much Coverage Do You Need?

This is one of the most common questions people ask.

A good starting point is to ask: If I were gone tomorrow, what financial gap would my family face?

You may want to consider:

  • Your mortgage balance

  • Other debts

  • Ongoing living expenses

  • Childcare costs

  • Future education expenses

  • Final expenses

Some people use a simple guideline like 10 times their annual income. But that is only a starting point. Your personal situation matters more than any rule of thumb.

For example, someone with no dependents and little debt may need very little coverage. A household with young children and a large mortgage may need much more.

The goal is to match coverage with real responsibilities.

Is Life Insurance Expensive?

Many people assume life insurance costs more than it does. In reality, term coverage can be very affordable, especially if you are young and in good health.

Your premium is based on factors such as:

  • Age

  • Health history

  • Smoking status

  • Coverage amount

  • Type of policy

The younger and healthier you are when you apply, the lower your premium is likely to be.

Waiting can increase the cost. Health can change over time. Securing coverage earlier can help lock in lower rates.

Who Should Consider Life Insurance?

Life insurance is not necessary for everyone. But it is important for many people.

You may want to consider coverage if:

  • Someone depends on your income

  • You share debts with a partner

  • You have children

  • You own a home

  • You want to leave money behind for loved ones

Even stay-at-home parents may need coverage. If they were not there, the cost of childcare and household support could be significant.

In Canada, life insurance benefits are generally paid tax-free to beneficiaries. This helps ensure that the full amount can be used for its intended purpose.

Final Thoughts

Life insurance is a practical tool. It helps protect the people you care about from financial hardship if something unexpected happens. It can provide stability, cover major expenses, and support your family’s future.

If you are unsure whether you need coverage, start by reviewing who depends on you and what financial responsibilities you carry. A short conversation can bring clarity and peace of mind.

If you would like to explore how life insurance fits into your overall strategy, I would be happy to guide you through the options and help you make an informed decision.

This is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.

Tax Lines to Look Out For on Your 2025 Canadian Tax Return

Tax Lines to Look Out For on Your 2025 Canadian Tax Return

The deadline for filing your 2025 income tax return is April 30, 2026. With several changes this year, from a lower federal tax rate to new benefits and eliminated credits, it pays to know what has changed before you file. This guide covers the key updates, deductions, and credits separated into sections for Individuals and Families, and Self-Employed Individuals.

For Individuals and Families

Federal Tax Rate Reduction

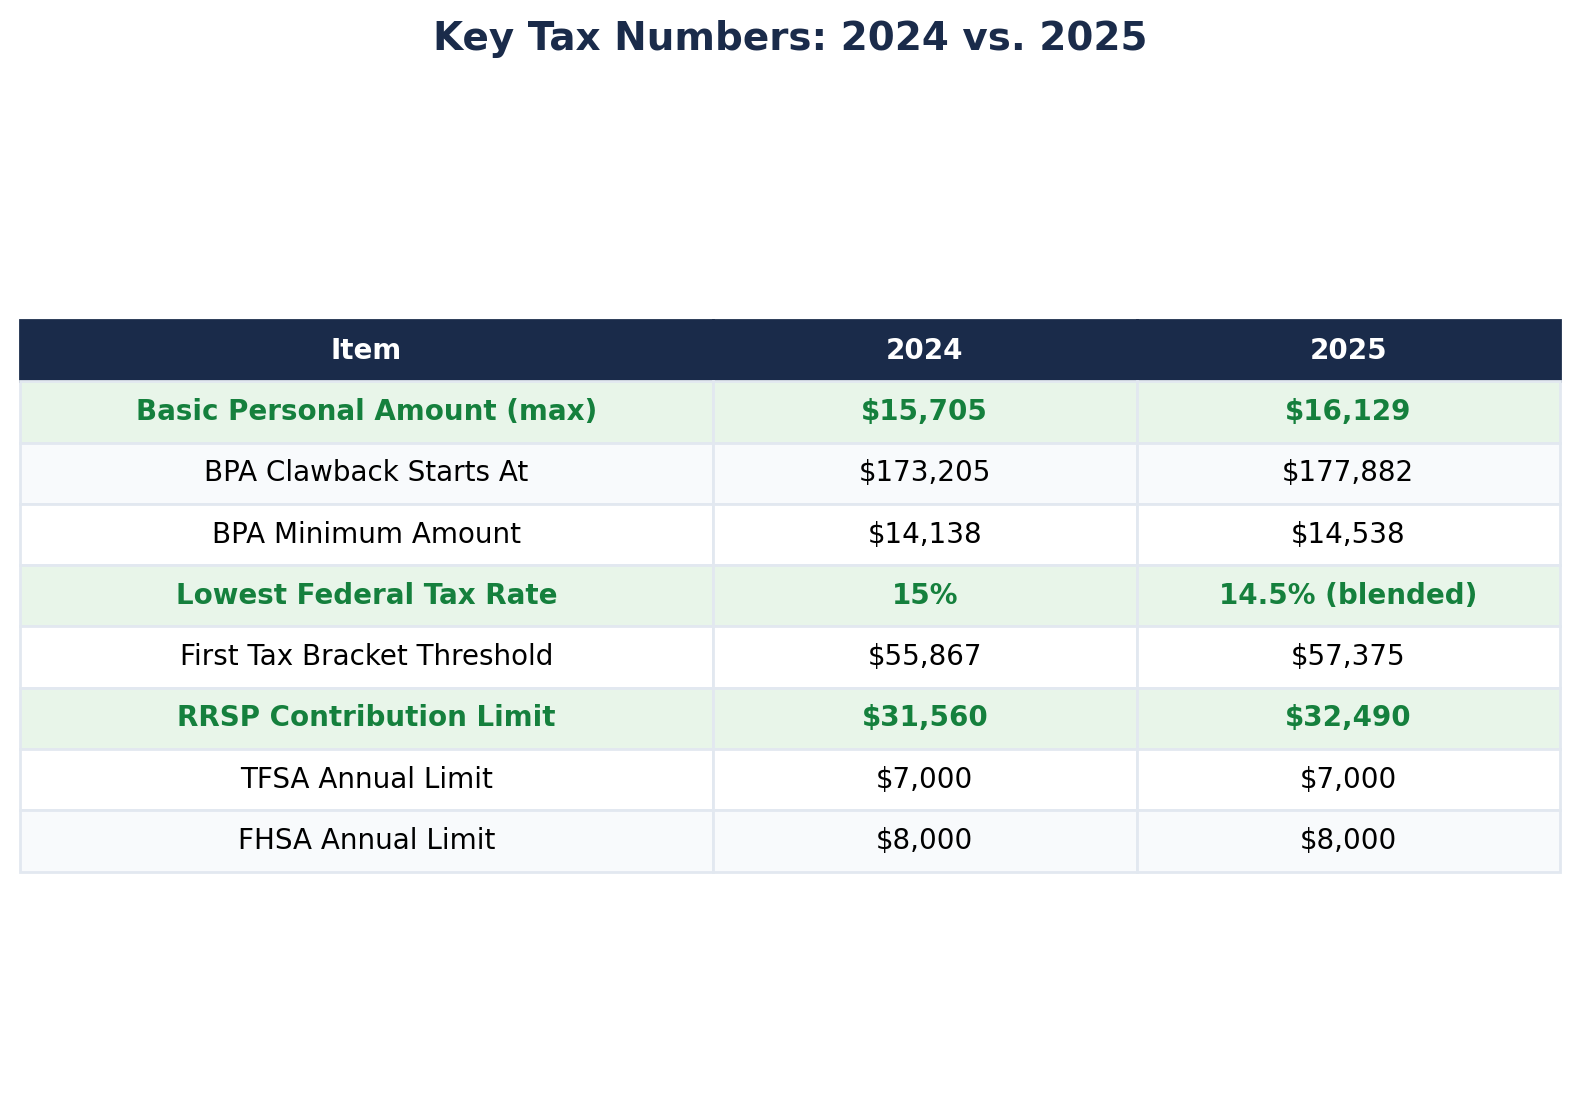
Effective July 1, 2025, under draft legislation introduced May 27, 2025, the lowest federal income tax rate was reduced from 15% to 14%. Because this change took effect halfway through the year, the blended rate for 2025 is 14.5%. This applies to the first $57,375 of taxable income and could save an individual up to $420 per year, or up to $840 for a two-income household.

Because the lowest rate also determines the value of most non-refundable tax credits, the government introduced a new top-up credit. This credit restores the full 15% value on eligible non-refundable credits claimed on amounts above $57,375, so the rate cut does not reduce the value of credits like the Basic Personal Amount, medical expenses, or tuition. This top-up credit will remain in place through the 2030 tax year.

Basic Personal Amount (BPA)

For 2025, the Basic Personal Amount has increased to $16,129 for taxpayers with net income up to $177,882. For those with net incomes above this amount, the BPA is gradually reduced, reaching a minimum of $14,538 at incomes of $253,414 or higher.

Capital Gains

The proposed increase in the capital gains inclusion rate from 50% to 66.67% on gains over $250,000 for individuals (and on all gains for corporations and most trusts) has been cancelled. The inclusion rate remains at 50% for all taxpayers. However, the lifetime capital gains exemption has been raised to $1,250,000 for qualifying dispositions of small business shares and farming or fishing property, up from $1,016,836.

Canada Disability Benefit

A new benefit became available in June 2025, providing up to $200 per month ($2,400 per year) for Canadian residents aged 18 to 64 who are approved for the Disability Tax Credit.

The benefit is income-tested, with the maximum amount generally available to single individuals with adjusted family net income of $23,000 or less. For couples, the threshold is higher (generally $32,500 after a working income exemption).

The benefit is gradually reduced as income increases. For single individuals, it is typically reduced by 20 cents for each dollar above the threshold. For couples, the reduction may be 20% or split at 10% each, depending on whether one or both partners qualify for the benefit.

What Has Been Eliminated

Canadian Journalism Tax Credit: The 15% non-refundable tax credit for qualifying digital news subscriptions (up to $75 per year) is no longer available for 2025.

Home Accessibility and Medical Expense Double-Claim: Under proposed measures announced in Budget 2025 and included in Bill C-15, 2025 is expected to be the final year that certain expenses qualifying for the Home Accessibility Tax Credit can also be claimed as a medical expense. Starting in 2026, these expenses will generally need to be claimed under only one provision and cannot be double-counted. Individuals planning eligible renovations may wish to take advantage of the current rules before this change takes effect.

Alternative Minimum Tax (AMT)

The updated AMT rules that took effect in 2024 continue to apply. These include a higher minimum tax rate, modified calculation for adjusted taxable income affecting foreign tax credits and minimum tax carryovers, and limited value on most non-refundable tax credits.

Popular Tax Credits and Deductions

Canada Training Credit (CTC) Eligible taxpayers aged 26 to 65 can claim this refundable tax credit to cover a portion of eligible tuition and fees for training or courses to enhance their skills.

Canada Caregiver Credit (CCC) This non-refundable tax credit supports individuals caring for family members or dependents with a physical or mental impairment. The amount varies based on the dependent’s relationship, net income, and circumstances.

Child Care Expenses Child care expenses, such as daycare, nursery schools, day camps, and boarding schools, are deductible if incurred to enable a parent or guardian to work, pursue education, or conduct research.

Disability Tax Credit (DTC) The DTC provides a non-refundable tax credit for individuals with disabilities or their caregivers to reduce the amount of income tax payable. For 2025, the disability amount is $10,138. Applicants must have a certified disability lasting at least 12 months. The expenses eligible for the disability supports deduction have also been expanded for 2025.

Moving Expenses Deductible moving expenses include transportation and storage costs, travel expenses, temporary living costs, and incidental expenses incurred when relocating at least 40 kilometers closer to a new work location, educational institution, or business location.

Interest Paid on Student Loans Interest paid on eligible student loans can be claimed as a non-refundable tax credit. The loans must be under federal, provincial, or territorial student loan programs.

Donations and Gifts Donations made to registered charities or other qualified organizations qualify for non-refundable federal and provincial tax credits. Typically, eligible amounts up to 75% of net income can be claimed. Note: due to the Canada Post strike in late 2024, eligible donations made in the first two months of 2025 can also be claimed on a 2024 return.

GST/HST Credit The GST/HST credit is a quarterly refundable payment designed to offset the impact of sales tax on low to moderate-income individuals and families. Eligibility is automatically assessed based on the annual tax return.

RRSP Contributions The maximum RRSP contribution for 2025 has increased to $32,490 (up from $31,560 in 2024), based on 18% of the previous year’s earned income. The TFSA annual contribution limit remains at $7,000 for 2025.

First Home Savings Account (FHSA) Contributions of up to $8,000 per year (lifetime limit of $40,000) are tax-deductible, grow tax-free, and qualifying withdrawals for a first home purchase are also tax-free. The FHSA can be used alongside the Home Buyers’ Plan, which maintains a withdrawal limit of $60,000.

For Self-Employed Individuals

CPP Contributions

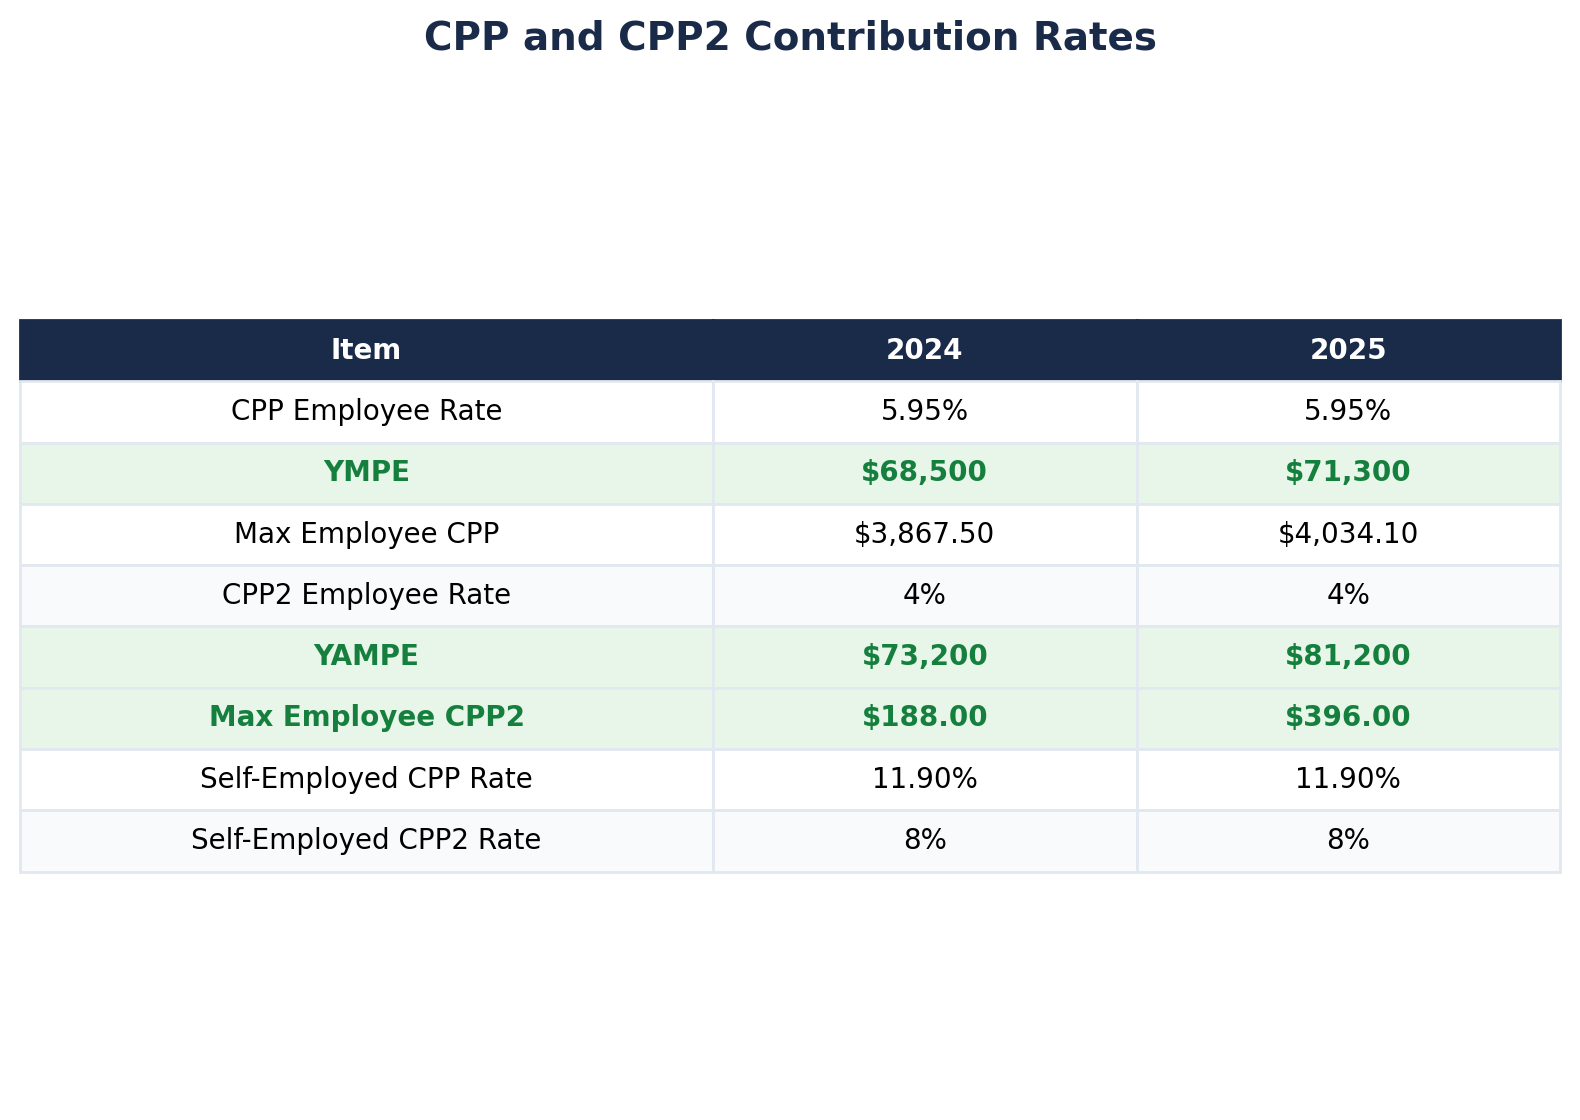
Self-employed individuals pay both the employee and employer portions of CPP, for a combined rate of 11.90% on earnings up to the YMPE ($71,300). For CPP2, the self-employed rate is 8% on earnings between $71,300 and $81,200, with a maximum CPP2 contribution of $792.

Filing and Payment Deadlines

  • Tax Return Deadline: June 15, 2026.

  • Balance due must be paid by April 30, 2026.

Reporting Business Income

Report income on a calendar-year basis for sole proprietorships and partnerships.

Digital Platform Operators

Reporting rules require platform operators to collect and report seller information to the CRA. If income is earned through a digital platform, it is important to ensure it is properly reported.

Filing season for 2025 returns opens February 23, 2026. With a lower federal tax rate, increased contribution limits, and several eliminated credits and taxes, reviewing these changes before filing can help maximize savings and avoid surprises. The CRA is also no longer mailing paper tax packages, so returns and forms are available online at canada.ca or by calling 1-855-330-3305.

Sources

Canada Revenue Agency. “Personal income tax: What’s new for 2025.” – Canada.ca – https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/about-your-tax-return/tax-return/completing-a-tax-return/whats-new.html

Canada Revenue Agency. “Important changes to the 2025 income tax package.” – Canada.ca – https://www.canada.ca/en/revenue-agency/news/newsroom/tax-tips/tax-tips-2025/important-changes-2025-income-tax-package.html

Canada Revenue Agency. “Maximum Pensionable Earnings and Contributions for 2025.” – Canada.ca – https://www.canada.ca/en/revenue-agency/news/newsroom/tax-tips/tax-tips-2024/canada-revenue-agency-announces-maximum-pensionable-earnings-contributions-2025.html

Canada Revenue Agency. “Basic Personal Amount.” – Canada.ca – https://www.canada.ca/en/revenue-agency/programs/about-canada-revenue-agency-cra/federal-government-budgets/basic-personal-amount.html

Canada Revenue Agency. “Tax rates and income brackets for individuals.” – Canada.ca – https://www.canada.ca/en/revenue-agency/services/tax/individuals/frequently-asked-questions-individuals/canadian-income-tax-rates-individuals-current-previous-years.html

“Budget 2025 – Tax Measures” (Home Accessibility Tax Credit change) – https://budget.canada.ca/2025/report-rapport/tm-mf-en.html

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

Ontario Budget 2026

What the 2026 Ontario Budget Means for Your Wallet and Your Business

If you live or run a business in Ontario, the provincial budget released on March 26, 2026 includes several changes that could affect your taxes, your home purchase, and your bottom line. Whether you are a small business owner, a home buyer, or an investor, there are a few measures worth paying attention to in this year’s budget.

Here is a breakdown of the biggest highlights and what they could mean for you.

Tax Break for Small Businesses

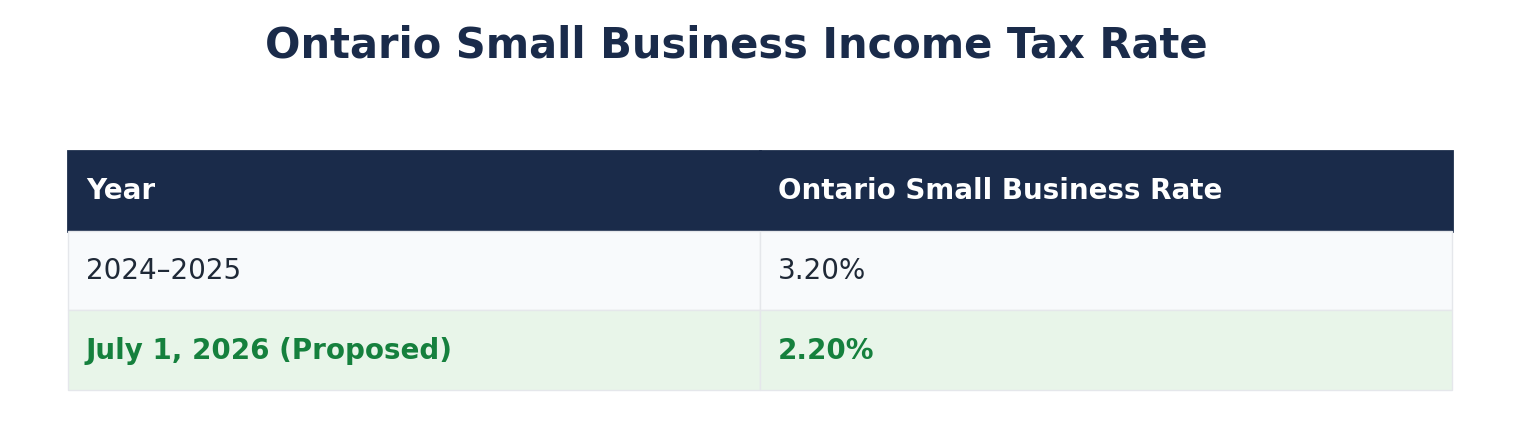
One of the biggest changes in this budget is a proposed cut to Ontario’s small business corporate income tax rate. The rate would fall from 3.2% to 2.2%, effective July 1, 2026. That is a reduction of more than 30%, and it applies to the first $500,000 of active business income earned by eligible small Canadian-controlled private corporations.

For a small business earning $500,000 in eligible income, that could mean savings of up to $5,000 per year. Because the change takes effect mid-year, the rate would be prorated for taxation years that straddle July 1, 2026.

For business owners who are managing rising costs or looking to invest in growth, that kind of savings could make a meaningful difference. It may also help free up cash for hiring, equipment purchases, or day-to-day operations.

Here is how the Ontario small business rate compares:

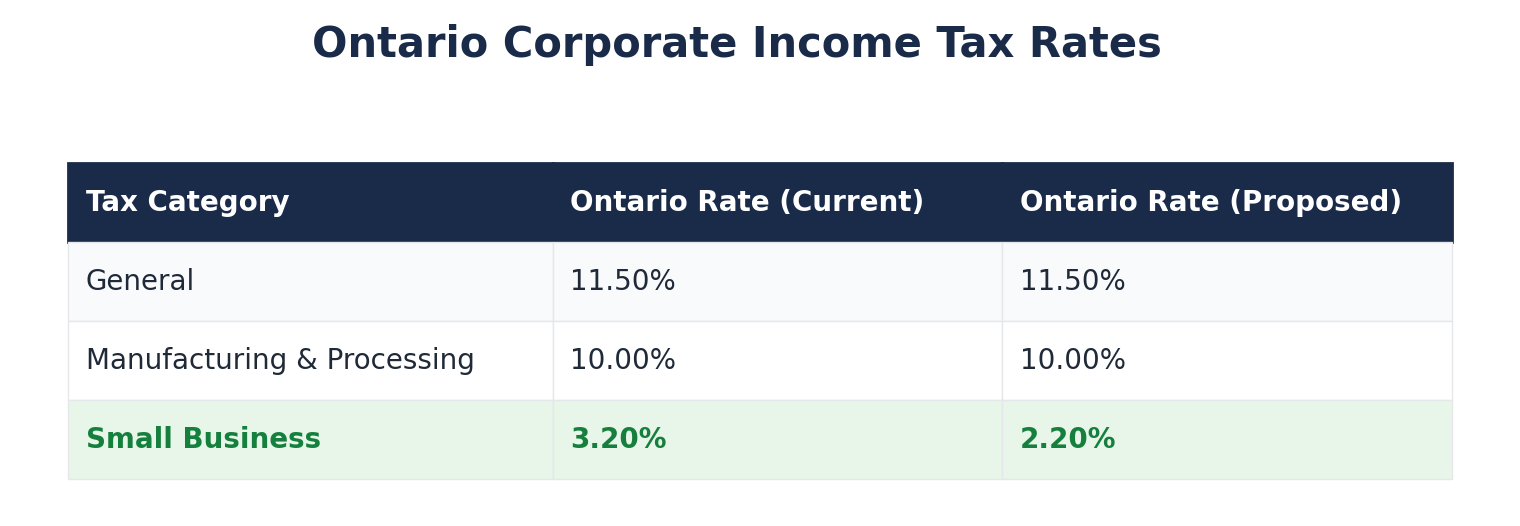
Here is a look at Ontario’s corporate income tax rates, with the small business rate reflecting the proposed change:

Small business rate applies to the first $500,000 of active business income. The proposed 2.2% rate takes effect July 1, 2026. Combined federal and provincial rates will vary depending on your specific situation — your accountant can confirm the exact figures for your business.

Non-Eligible Dividends

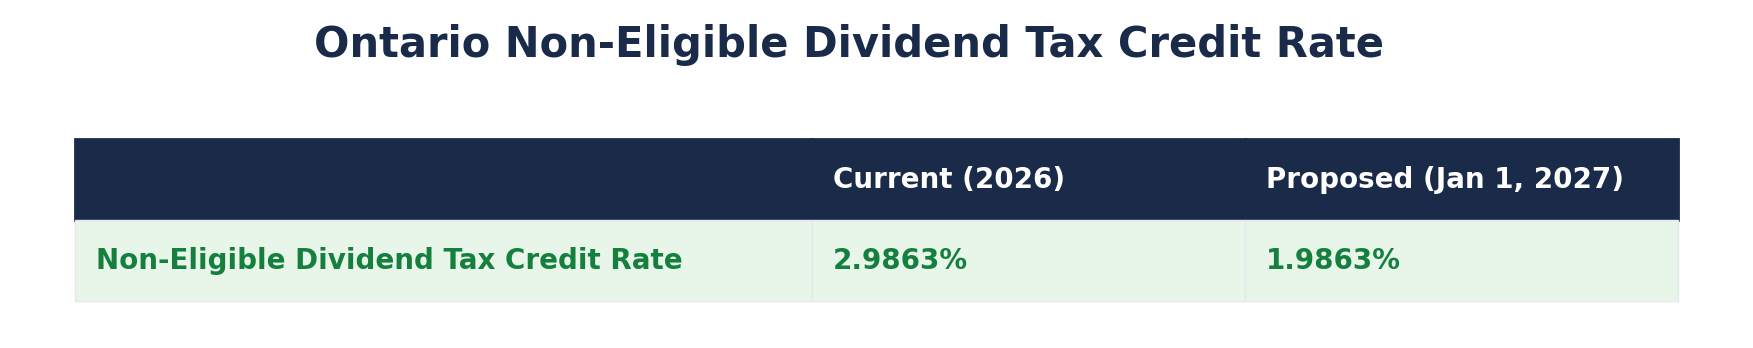
If you receive non-eligible dividends, or if you own a corporation and pay yourself dividends, there is another change to note. Ontario is proposing to reduce the non-eligible dividend tax credit rate from 2.9863% to 1.9863%, effective January 1, 2027.

This change is linked to the lower small business corporate tax rate. In general, when corporate tax rates fall, dividend tax credit rates are adjusted to reflect the change in after-tax corporate income.

The budget does not directly state combined top marginal rates, but the effect of reducing the dividend tax credit is that the tax you owe on non-eligible dividends would increase. If dividends are part of your income strategy, it may be worth reviewing how this could affect your overall tax picture.

More Flexibility for Employee Benefit Plans

If you offer employee benefits through a funded benefit plan, Ontario is proposing a change that could improve cash flow. Starting April 1, 2026, funded benefit plans would be able to elect to be treated as unfunded plans for Insurance Premium Tax purposes.

In practical terms, that means the tax would be triggered when benefits are paid out rather than when contributions are made into the plan. If you sponsor a benefit plan, it may be worth checking whether this election is useful for your business.

Faster Write-Offs for Business Equipment

The budget also proposes accelerated deductions for depreciable assets, in parallel with changes announced by the federal government. Ontario says these measures would lower the cost of investing in a broad range of assets, and they would take effect following the passage of federal legislation.

For business owners considering major purchases, faster deductions can improve cash flow by allowing more of the cost to be deducted sooner rather than spread over several years.

The budget also proposes to let the Regional Opportunities Investment Tax Credit expire effective January 1, 2027, with expenditures incurred on or before December 31, 2026 still eligible.

Keeping Costs Down for Families

Beyond tax changes, the budget includes several measures aimed at easing everyday costs for Ontario families. The Ontario Electricity Rebate continues, the Ontario One Fare Program is being extended for another two years, and tolls on the provincially owned portion of Highway 407 East have been removed.

Ontario says the One Fare extension could save daily transit users in the Greater Toronto and Hamilton Area up to $1,600 per year, while the Electricity Rebate continues to reduce electricity bills for households.

The budget also includes support for families and individuals through a range of spending measures in health care, education, and social programs.

HST Relief for New Home Buyers

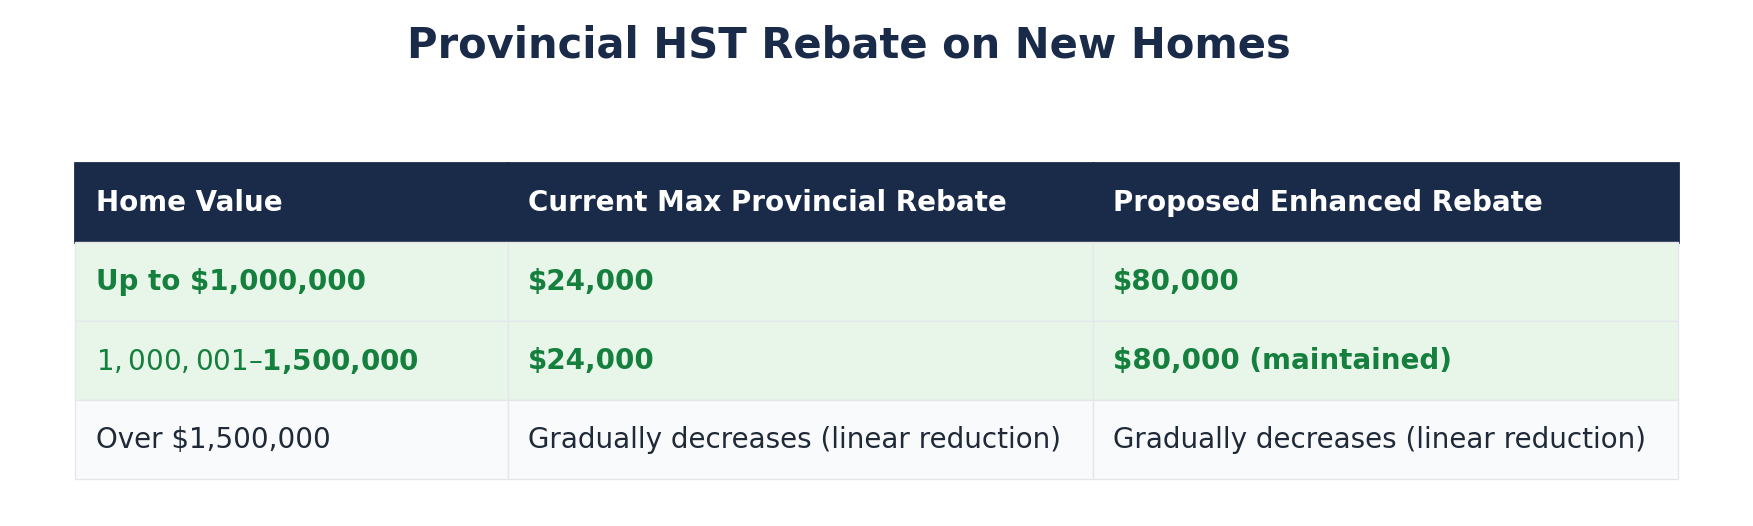
If you are thinking about buying a new home or condo, the budget includes a major temporary expansion of Ontario’s housing rebates. Ontario is proposing to provide further relief for eligible buyers of new homes by removing the full 13% HST on qualifying new homes valued up to $1 million, subject to federal legislation. The maximum rebate amount would be maintained for homes valued up to $1.5 million.

The federal government has agreed to cost-share, subject to the passage of federal legislation, to cover the federal 5% portion being removed. The enhanced rebate is proposed to apply from April 1, 2026 to March 31, 2027.

Here is a quick look at what the proposed rebate change could mean depending on your home’s value:

The budget also proposes to eliminate the provincial HST New Housing Rebate and the New Residential Rental Property Rebate after the enhancement period ends, with further transitional details to be set out later.

Ontario is also proposing to align its first-time home buyer rebate with the federal GST/HST First-Time Home Buyers’ Rebate. These changes require federal regulatory changes, and Ontario says it will continue working with the federal government to support implementation. Under the proposal, the rebate would apply to agreements of purchase and sale entered into on or after March 20, 2025 and before 2031.

The Big Picture

Ontario is projecting planned capital investments of more than $210 billion over 10 years, including $37 billion in 2026–27. The province says these investments will support highways, hospitals, transit, and other infrastructure across Ontario.

At the same time, the budget is being framed as part of the province’s response to tariffs and broader economic uncertainty.

What This Means for You

This budget touches a wide range of financial decisions. If you own a small business, you may want to review your tax strategy in light of the lower corporate rate and accelerated deductions. If you are a first-time home buyer or considering a new build, the enhanced HST rebate could create a valuable but time-limited opportunity. If you receive non-eligible dividends, the tax credit change beginning in 2027 is something to plan for now.

Every situation is different, so the best next step is to review these changes and see which ones apply to you.

Sources

Ontario Ministry of Finance, 2026 Ontario Budget: A Plan to Protect Ontario — Highlights – https://budget.ontario.ca/2026/highlights.html

Ontario Ministry of Finance, Annex: Details of Tax Measures and Other Legislative Initiatives – https://budget.ontario.ca/2026/annex.html

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

2026 Canada Money Facts

brandableContent

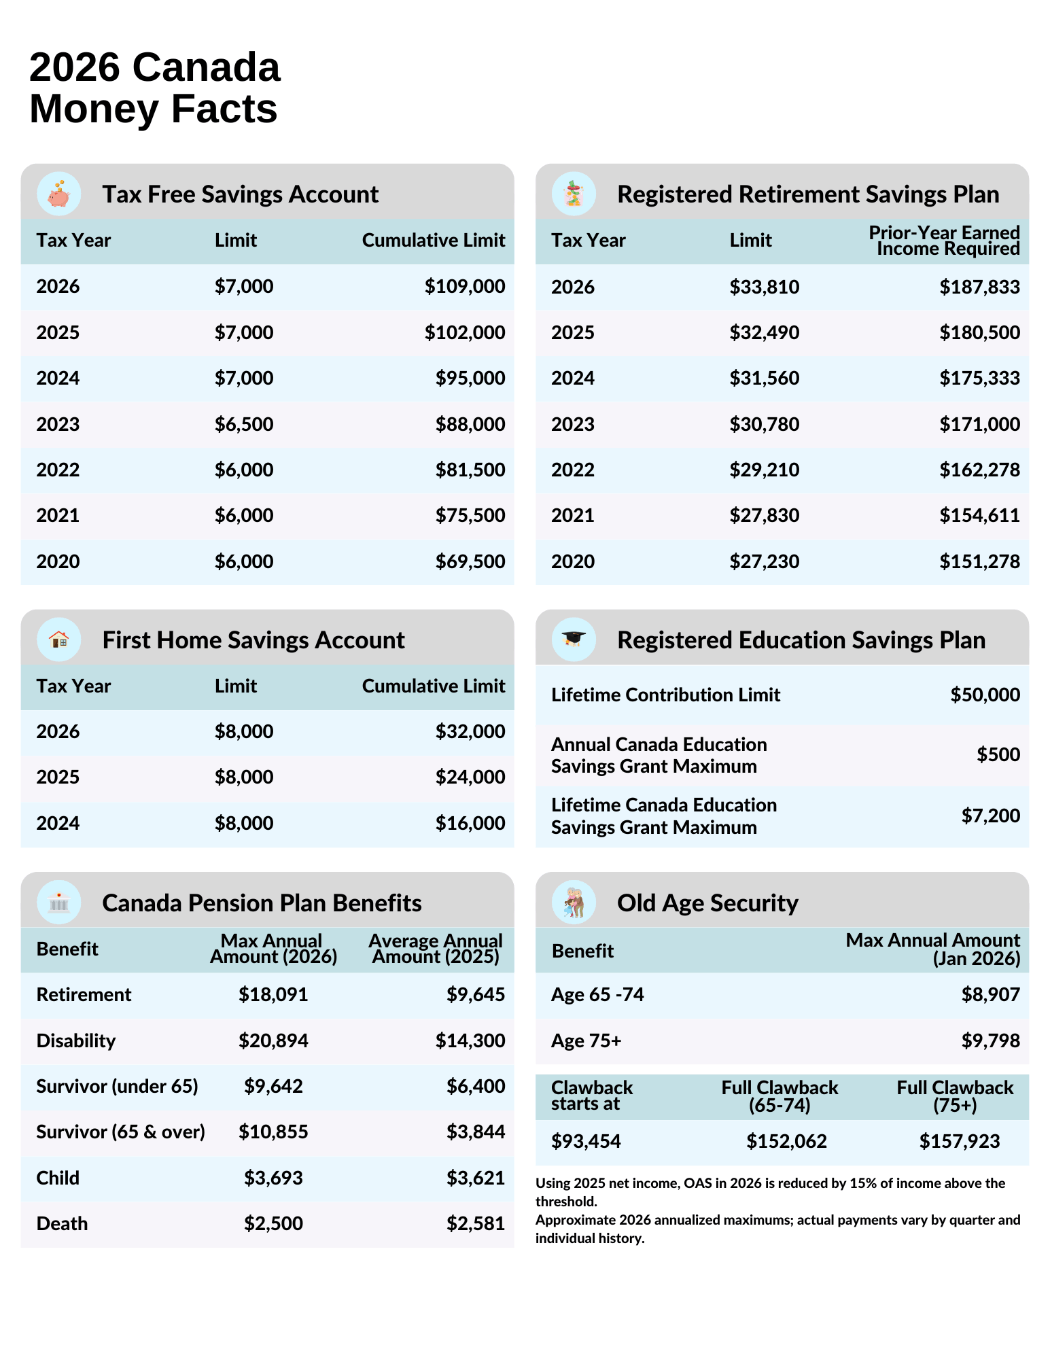
Staying informed about financial limits and government benefits is essential for effective planning. The 2026 Canada Money Facts infographic provides a clear snapshot of key savings limits and retirement benefits, including TFSA, RRSP, FHSA, RESP, CPP, and OAS.
Here’s what you need to know for 2026.

Tax-Free Savings Account (TFSA)

The 2026 TFSA contribution limit is $7,000, bringing the cumulative contribution room to $109,000 for individuals who have been eligible since the TFSA was introduced in 2009 and have never contributed.

It’s important to note that total TFSA room depends on personal circumstances. Eligibility begins at age 18 or 19, depending on the province, and newcomers to Canada accumulate room only from the year they become residents. If you became eligible after 2009, your cumulative limit will be lower based on the years you qualified.

The TFSA remains one of the most flexible savings tools available, allowing investments to grow tax-free and withdrawals to be made without triggering tax.

Registered Retirement Savings Plan (RRSP)

For 2026, the RRSP contribution limit is $33,810, calculated as 18% of earned income from the prior year, up to the annual maximum. To fully maximize RRSP contributions for 2026, an individual would need prior-year earned income of approximately $187,833.

RRSPs continue to be a cornerstone of retirement planning, offering tax-deductible contributions and tax-deferred growth, which can be especially valuable during higher-income earning years.

First Home Savings Account (FHSA)

The FHSA annual contribution limit remains $8,000 in 2026, with a cumulative contribution limit of $32,000.

As with previous years, FHSA eligibility begins at the age of majority (18 or 19, depending on the province), and contributions can only be made once the account is opened. Since the FHSA was introduced in 2023, not everyone will have access to the full cumulative room.

FHSA contributions are tax-deductible, and qualifying withdrawals for a first home purchase are tax-free, making this account a powerful planning tool for first-time homebuyers.

Registered Education Savings Plan (RESP)

RESP limits remain unchanged in 2026:

  • Lifetime contribution limit: $50,000 per beneficiary

  • Annual Canada Education Savings Grant (CESG): up to $500

  • Lifetime CESG maximum: $7,200

RESPs continue to be an effective way to save for a child’s post-secondary education while benefiting from government grants and tax-deferred growth.

Canada Pension Plan (CPP) & Old Age Security (OAS)

CPP benefit amounts increase for 2026:

  • Maximum CPP retirement benefit: $18,091 annually

  • Maximum CPP disability benefit: $20,894 annually

Actual CPP payments depend on an individual’s contribution history and the age at which benefits begin, but these figures provide a useful benchmark for planning purposes.

OAS payments for January 2026 are estimated at:

  • Ages 65–74: up to $8,907 annually

  • Ages 75+: up to $9,798 annually

OAS is subject to a clawback for higher-income retirees. In 2026, the clawback begins when 2025 net income exceeds $93,454. Full clawback thresholds are approximately $152,062 for ages 65–74 and $157,923 for ages 75 and over. OAS benefits are reduced by 15% of income above the threshold.

This 2026 infographic is designed as a quick reference to help Canadians stay informed and make confident planning decisions. Whether you’re maximizing registered accounts, preparing for retirement income, or saving for a home or education, understanding these updated limits helps ensure you’re making the most of available opportunities.

Staying proactive and informed in 2026 can make a meaningful difference in your long-term financial success.